Introduction to Cross-Chain Liquidity
What Is Cross-Chain Liquidity?
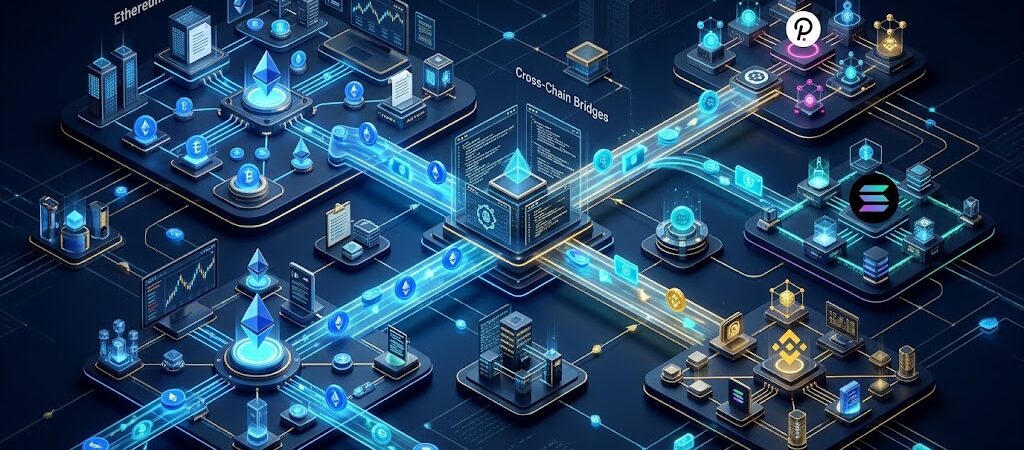
Cross-chain liquidity protocols help connect separate blockchain ecosystems, allowing users and applications to move capital, access decentralized financial services, and interact with supported assets across different networks. the blockchain industry has grown into a diverse network of independent ecosystems, each offering its own applications, digital assets, financial services, and technological advantages. Ethereum supports a broad decentralized finance (DeFi) ecosystem, Solana focuses on high-speed transactions, and other networks provide specialized environments for smart contracts, payments, gaming, and digital asset management. However, this expansion has created an important challenge: digital assets and available capital are often distributed across separate blockchain networks.
Cross-chain liquidity refers to the ability to transfer, access, exchange, or deploy digital assets and financial capital across different blockchain ecosystems. It enables users, traders, decentralized applications, and liquidity providers to interact with assets and financial opportunities beyond the boundaries of a single blockchain.
For example, a user holding assets on Ethereum may want to access a decentralized exchange operating on another network. Without an appropriate cross-chain mechanism, moving those assets and using them in the destination ecosystem can involve several separate steps. Cross-chain infrastructure aims to make these interactions more accessible by coordinating asset transfers, cross-chain messages, swaps, and other transactions.
The concept extends beyond simply moving tokens between networks. Effective cross-chain liquidity also concerns how efficiently capital reaches its destination, whether sufficient liquidity exists to complete a transaction, what fees users must pay, and which security assumptions govern the process.
As decentralized finance continues to develop, cross-chain liquidity is becoming an important part of the infrastructure connecting blockchain-based financial markets.
Why Cross-Chain Liquidity Matters in Modern Blockchain Finance
In the early development of decentralized finance, many financial activities were concentrated within individual blockchain ecosystems. Users generally acquired assets, supplied liquidity, traded tokens, and interacted with decentralized applications on the network where their assets were held.
However, the growth of alternative Layer 1 blockchains, Layer 2 scaling networks, and specialized DeFi platforms has changed this landscape. Different ecosystems now compete to attract users and capital by offering distinct transaction costs, performance characteristics, financial products, and incentives.
This creates opportunities but also introduces fragmentation.
A blockchain may offer attractive lending rates while another provides deeper trading liquidity for a particular asset. A third network might support an application with lower transaction fees or features unavailable elsewhere. If capital cannot move efficiently between these environments, users may struggle to take advantage of opportunities across the wider market.
Cross-chain liquidity helps address this challenge by connecting otherwise separated pools of capital.
For traders, it can improve access to trading pairs and decentralized exchanges across networks. For decentralized applications, it can expand the range of assets and users they can serve. For liquidity providers, it creates additional opportunities to allocate capital across different markets, although these opportunities also involve additional costs and risks.
Cross-chain connectivity does not automatically guarantee better prices or deeper liquidity. The actual benefits depend on available trading depth, transaction costs, network conditions, bridge security, and the reliability of the underlying infrastructure.
Nevertheless, enabling capital to move between blockchain ecosystems is an important step toward a more connected decentralized financial system.
Understanding Blockchain Liquidity Fragmentation
Liquidity fragmentation occurs when available capital is distributed across multiple markets, platforms, or blockchain networks rather than being readily accessible through a single connected market.
Consider a hypothetical example involving three blockchain ecosystems. Ethereum hosts a decentralized exchange with substantial liquidity for a particular token. A second blockchain offers a growing lending market, while a third supports a new decentralized application with attractive features.
A user may hold the relevant token on Ethereum but want to use it on the third network. Although the same token or a related representation may be available across these ecosystems, the liquidity pools, trading infrastructure, and transaction environments are not necessarily connected.
The user might need to bridge assets, exchange one token for another, pay network fees, and interact with the destination application. Depending on the infrastructure, these steps may be completed through a single interface or require several separate transactions.
This fragmentation creates several challenges:
- Limited access to capital: Assets held on one blockchain may not be directly available for applications on another network.
- Uneven liquidity distribution: Some ecosystems may have deep trading markets, while others experience lower liquidity and greater price impact.
- Higher transaction costs: Moving assets across networks can involve bridge fees, gas costs, and exchange fees.
- Complex user experiences: Different wallets, network configurations, token representations, and transaction requirements can make cross-chain activity difficult.
- Market inefficiencies: Differences in prices and liquidity across networks may create opportunities, but executing transactions profitably can be difficult.
Cross-chain liquidity infrastructure attempts to reduce these barriers. Its effectiveness depends on how securely and efficiently it connects markets, rather than simply how many blockchains it supports.
How Cross-Chain Liquidity Connects Different Ecosystems
Cross-chain liquidity can be enabled through several types of infrastructure. These systems have different technical designs, trust assumptions, and methods of moving or exchanging assets.
Blockchain bridges are one important category. Depending on their design, bridges may lock assets on a source chain and issue corresponding representations on a destination chain, or use liquidity pools to facilitate transfers. Other systems rely on messaging protocols, coordinated smart contracts, or specialized networks to communicate between blockchains.
Cross-chain decentralized exchanges and aggregators can also help users exchange assets across networks. Rather than requiring users to identify every individual transaction themselves, these systems may coordinate routing, swaps, and transfers through available liquidity sources.
Some protocols use liquidity providers to make assets available on destination networks. Others rely on mechanisms that coordinate transactions across multiple chains or use specialized infrastructure to support cross-chain execution.
These approaches are not interchangeable. A bridge that transfers an asset representation operates differently from a system that performs a cross-chain swap, and both differ from a messaging protocol that simply communicates information between networks.
Understanding these distinctions is essential when evaluating how capital actually moves.
For example, transferring a token from one network to another does not necessarily mean that the original token has physically moved between blockchains. Depending on the system, the process might involve locking the original asset, minting a corresponding token, releasing assets from a liquidity pool, or executing coordinated transactions across networks.
The exact mechanism determines the transaction’s costs, speed, liquidity requirements, and security considerations.
Cross-Chain Liquidity and the Growth of Decentralized Finance
Decentralized finance has introduced financial services that operate through blockchain-based smart contracts rather than relying exclusively on traditional intermediaries. These services include token exchanges, lending and borrowing, derivatives, yield strategies, and liquidity provision.
As DeFi expands across multiple networks, users increasingly encounter financial opportunities distributed among different ecosystems.
Cross-chain liquidity can help connect these opportunities. A user may be able to transfer assets to a network with a lending market, exchange tokens through a cross-chain trading system, or deploy capital into a supported decentralized application on another blockchain.
Developers can also benefit from improved connectivity. Applications may gain access to users and assets originating from other networks, potentially expanding their addressable markets. However, achieving this connectivity requires careful consideration of smart contract security, asset compatibility, transaction finality, and the reliability of cross-chain communication.
Liquidity providers face a different set of considerations. Providing assets across several networks may diversify their opportunities, but it can also expose them to additional smart contract vulnerabilities, bridge failures, inventory imbalances, and operational complexity.
Consequently, cross-chain liquidity should not be viewed simply as a mechanism for increasing the amount of capital available to DeFi. It is also a system for coordinating that capital across environments with different technical and economic characteristics.
The Difference Between Cross-Chain Transfers and Cross-Chain Liquidity
Although the terms are closely related, cross-chain transfers and cross-chain liquidity describe different aspects of blockchain interoperability.
A cross-chain transfer concerns moving an asset or its representation from one blockchain environment to another. Its primary objective is to make the asset available on the destination network.
Cross-chain liquidity concerns the broader ability to access and use capital across networks. This includes the availability of assets for trading, the depth of liquidity pools, the efficiency of transaction routing, and the ability to execute financial activities across connected ecosystems.
Consider a user transferring a stablecoin from one blockchain to another. The transfer may succeed, but the destination network might have limited liquidity for exchanging that stablecoin into another asset. The user could therefore encounter significant price impact or find that the desired transaction cannot be completed efficiently.
In this situation, the transfer mechanism has delivered the asset, but the destination market does not necessarily provide sufficient liquidity for the user’s intended activity.
The distinction matters because a technically successful transfer does not guarantee an economically efficient transaction.
A well-designed cross-chain liquidity system must consider both the movement of assets and the conditions under which those assets can be used. Depending on the application, this may involve access to deeper liquidity pools, efficient routing, reliable settlement, transparent fees, and safeguards against transaction failures.
Key Factors That Determine Cross-Chain Liquidity Efficiency
Several factors influence how effectively capital moves between blockchain ecosystems.
Liquidity depth: The amount of available capital in relevant markets influences how much a user can trade without significantly affecting the price. Deeper liquidity generally supports larger transactions with lower price impact, all else being equal.
Transaction costs: Users may pay source-chain gas fees, destination-chain gas fees, bridge charges, swap fees, and other execution costs. These expenses can reduce the benefits of moving capital between networks.
Transaction speed: Cross-chain activity may require waiting for source-chain confirmations, proof verification, message delivery, or destination-chain execution. Different protocols handle these steps differently.
Security and trust assumptions: Cross-chain systems depend on mechanisms that verify events and authorize actions between networks. Their security may rely on validator sets, multisignature arrangements, cryptographic proofs, smart contracts, or other verification methods.
Asset compatibility: A token’s availability on multiple networks does not necessarily mean that every version represents an identical claim or has the same redemption guarantees. Users must understand whether they are dealing with a native asset, a wrapped token, or another form of representation.
Routing efficiency: Cross-chain aggregators and execution systems may evaluate different routes to find an appropriate combination of transfers, swaps, and liquidity sources. The quality of a route depends on current prices, available liquidity, costs, and execution risks.
Market conditions: Liquidity can change rapidly as traders move capital, incentives expire, or market volatility increases. A route that is efficient under normal conditions may become expensive or unavailable during periods of congestion.
These factors interact with one another. A route with low fees may offer limited liquidity, while a route with deeper markets may require additional transactions. Evaluating cross-chain liquidity therefore requires looking at the complete transaction rather than focusing on a single performance metric.
What Readers Should Understand About Cross-Chain Capital Movement
The central idea behind cross-chain liquidity is that blockchain networks should not have to function as completely isolated financial environments.
Different blockchains can specialize in particular applications, performance requirements, or financial services. However, when assets and liquidity are difficult to access across those networks, users may face unnecessary friction and capital may remain concentrated in separate ecosystems.
Cross-chain liquidity infrastructure seeks to connect these markets while managing the technical, financial, and security challenges involved.
Its long-term importance will depend on whether these systems can provide dependable execution, competitive transaction costs, meaningful liquidity access, and transparent security guarantees. Simply connecting more networks is not enough if users cannot move capital safely or complete transactions at reasonable prices.
As the blockchain industry evolves, the ability to coordinate assets and financial activity across ecosystems could become an increasingly important part of decentralized finance.
Understanding the fundamentals of cross-chain liquidity provides the foundation for examining the bridges, liquidity pools, interoperability protocols, and routing mechanisms that make this connectivity possible.
Understanding Liquidity Across Blockchain Ecosystems
What Does Liquidity Mean in Blockchain Markets?
Liquidity is one of the most important concepts in cryptocurrency markets and decentralized finance. It describes how easily an asset can be bought, sold, exchanged, or used in a financial transaction without causing a significant change in its market price.
In traditional financial markets, liquidity is often associated with the availability of buyers and sellers, trading volume, and the difference between buying and selling prices. Cryptocurrency markets follow similar principles, but blockchain technology introduces additional factors, including smart contract-based liquidity pools, automated market makers, transaction fees, and network-specific asset availability.
For example, a cryptocurrency may have a substantial market capitalization but limited liquidity on a particular decentralized exchange. Although the asset’s total valuation may appear large, traders might struggle to execute large orders without experiencing significant price impact.
Conversely, an asset with deep liquidity on a particular trading platform may be exchanged more efficiently because sufficient capital is available to support transactions.
Within decentralized finance, liquidity can take several forms. It may exist in token trading pools, lending markets, borrowing protocols, derivatives platforms, or other applications that require users to supply assets. Each environment has different requirements and mechanisms for making capital available.
Cross-chain liquidity extends this concept across multiple blockchain ecosystems. Instead of examining liquidity within a single network, it considers how capital can be accessed and utilized across connected blockchains.
Understanding this distinction helps explain why moving assets between networks is only one part of creating a connected blockchain financial system.
How Independent Blockchain Ecosystems Manage Liquidity
Every blockchain ecosystem has its own technical infrastructure, applications, users, and financial markets. Even when two networks support similar tokens or decentralized applications, their liquidity is not automatically shared.
Ethereum, Solana, Arbitrum, Optimism, and other blockchain networks operate within different execution environments and use different mechanisms for processing transactions. Their applications may also rely on separate smart contracts, token standards, wallet integrations, and liquidity providers.
As a result, capital deposited into a liquidity pool on one network generally remains available to that particular pool unless a supported mechanism allows it to be accessed elsewhere.
Consider a hypothetical situation in which a decentralized exchange on Ethereum has a deep trading pool for a stablecoin and another cryptocurrency. A similar exchange on a different blockchain might offer the same trading pair but have substantially less capital available.
The existence of both markets does not mean they automatically share liquidity. Each pool maintains its own balances, pricing conditions, and trading activity.
A trader using the second network may experience greater price impact when executing a large transaction. Alternatively, the trader might choose to move assets to another network, provided the expected benefits justify the additional costs and risks.
This separation can encourage innovation because individual ecosystems can develop financial products suited to their users. However, it also creates challenges when users want to access opportunities distributed across multiple networks.
Cross-chain liquidity mechanisms aim to reduce these barriers by helping users access assets and markets beyond the blockchain where their capital initially resides.
Liquidity Pools and Automated Market Makers
Liquidity pools are smart-contract-based reserves of digital assets used to facilitate transactions in decentralized finance. Instead of relying exclusively on a traditional order book matching buyers with sellers, many decentralized exchanges use automated market makers (AMMs) to determine prices according to predefined mathematical rules and the assets available in their pools.
Liquidity providers deposit supported assets into these pools. In return, they may receive a share of trading fees or other incentives, depending on the protocol’s design.
For example, imagine a hypothetical liquidity pool containing a cryptocurrency and a stablecoin. A trader can exchange one asset for the other directly through the pool. The transaction changes the relative quantities of the assets, which can also change the pool’s quoted price.
When a pool has substantial liquidity relative to the size of a trade, the transaction may have a smaller price impact. When liquidity is limited, the same trade can move the price more significantly.
Liquidity pools are important to cross-chain finance because they can provide the capital needed to execute transactions on different networks.
Some cross-chain systems rely on liquidity providers who maintain assets on multiple supported blockchains. When a user initiates a transfer or swap, the system may use destination-side liquidity to deliver the requested asset, while a separate process manages the corresponding settlement or inventory adjustments.
This approach can reduce the need for every user to wait for a conventional asset-locking and token-minting process. However, the system still depends on sufficient available liquidity, secure transaction coordination, and reliable settlement mechanisms.
It is also important to distinguish between liquidity pools on a single blockchain and systems that coordinate liquidity across several networks. A pool on one chain does not become cross-chain merely because the protocol also operates on another chain.
The connection requires infrastructure that can coordinate assets, transactions, and settlement across the participating environments.
Liquidity Fragmentation Across Layer 1 and Layer 2 Networks
Liquidity fragmentation is especially relevant as the blockchain industry expands beyond individual Layer 1 networks into Layer 2 scaling ecosystems.
Layer 1 blockchains provide their own underlying transaction and settlement infrastructure. Layer 2 networks generally operate on top of an underlying blockchain or use another settlement arrangement to support transaction execution, scalability, or reduced costs.
These systems can offer different performance characteristics and financial opportunities. However, assets and liquidity deployed on one network may not be directly available on another.
For example, a user might hold assets on Ethereum mainnet while a decentralized lending application operates on an Ethereum Layer 2 network. Although the Layer 2 network is associated with Ethereum, the user may still need to complete a supported transfer or bridging process before using those assets in the destination application.
Different Layer 2 networks may also maintain separate liquidity pools, decentralized exchanges, and lending markets.
This can create a situation in which several networks support similar financial products but maintain different levels of liquidity. A trader may find competitive pricing on one network but weaker liquidity on another.
The problem is not necessarily a lack of total capital across the entire blockchain industry. Instead, the capital may be distributed in ways that prevent users from accessing it efficiently.
Cross-chain liquidity infrastructure attempts to connect these markets by coordinating transfers, swaps, and access to liquidity across supported networks.
Nevertheless, Layer 2 connectivity introduces its own considerations. Withdrawal procedures, settlement arrangements, proof verification, bridge security, and differences between network designs can affect the time and cost required to move assets.
Users must therefore evaluate the specific transfer mechanism rather than assuming that every network associated with the same Layer 1 blockchain offers seamless liquidity access.
Native Assets, Wrapped Tokens, and Liquidity Availability
An important aspect of cross-chain liquidity is understanding the difference between native assets and representations of assets on other networks.
A native asset is an asset issued or maintained within its original blockchain environment. For example, ETH is the native asset used to pay transaction fees on Ethereum, while SOL serves this role on Solana.
When a user wants to access an asset in another blockchain ecosystem, the process may involve creating or using a representation of that asset on the destination network.
Wrapped tokens are one common example. Depending on the protocol, a wrapped token may represent an underlying asset held in custody, locked in a smart contract, or managed through another verification and redemption arrangement.
These representations can help users access financial applications that do not directly support the original asset. However, the representation introduces additional considerations regarding redemption, custody, smart contract security, and the mechanism that maintains its relationship with the underlying asset.
A token representing an asset on one blockchain does not automatically possess the same liquidity as the original asset on another network.
For example, a wrapped version of a cryptocurrency might trade actively on a destination blockchain but have a relatively shallow liquidity pool. A user attempting to sell a large amount could experience significant price impact even if the underlying asset has deep markets elsewhere.
The ability to move a token representation across networks therefore does not guarantee that users can exchange it efficiently or redeem it under every market condition.
Cross-chain liquidity systems must account for these differences when routing transactions and estimating execution costs.
Liquidity Depth, Trading Volume, and Price Impact
Three related concepts help explain why liquidity conditions differ across blockchain ecosystems: liquidity depth, trading volume, and price impact.
Liquidity depth refers to the amount of capital available to support transactions at or near prevailing market prices. Deeper markets can generally accommodate larger trades with less price disruption.
Trading volume measures the amount of trading activity occurring over a specified period. High volume can indicate active market participation, but it does not automatically prove that a market has sufficient liquidity to support a large transaction at a stable price.
Price impact describes how a transaction changes the execution price relative to the price that would have applied before the trade. Its magnitude depends on the market structure, available liquidity, and transaction size.
These distinctions are particularly important when comparing markets across multiple blockchains.
Suppose a token has substantial trading activity on one network but limited liquidity on another. A small transaction on the second network might execute without difficulty, while a larger order could produce a substantially worse price.
A cross-chain aggregator may attempt to find a more efficient route by comparing available pools and transaction paths. It might route a trade through another supported market or divide execution among several liquidity sources, depending on its design.
However, routing systems cannot eliminate the underlying economic limitations of thin markets. If sufficient liquidity is unavailable, the user may still face high price impact, additional fees, or a failed transaction.
Furthermore, a route that appears attractive when first quoted may become less favorable before execution because of market movements, changing pool balances, network congestion, or competing transactions.
Reliable cross-chain liquidity therefore requires accurate price information, realistic fee estimates, and mechanisms for handling changes in market conditions.
How Liquidity Providers Support Cross-Chain Capital Movement
Liquidity providers play an important role in connecting blockchain markets. They supply assets to trading pools, maintain inventories, and may participate in specialized systems designed to facilitate cross-chain swaps or transfers.
In a traditional decentralized exchange, a liquidity provider might deposit two tokens into a pool on a single blockchain. Traders then exchange those assets through the pool according to the protocol’s pricing mechanism.
In a cross-chain liquidity network, providers may maintain supported assets across several blockchain environments. This allows the system to facilitate transactions using capital already available on the destination network.
For example, imagine that a user wants to exchange an asset on Blockchain A for a stablecoin on Blockchain B. A supported cross-chain system might arrange for a liquidity provider to deliver the stablecoin on Blockchain B while another part of the process settles the provider’s position or manages its inventory.
The user experiences a coordinated cross-chain transaction, while the underlying system must ensure that the provider receives the appropriate settlement and that the transaction follows the protocol’s rules.
Liquidity providers may earn fees for supplying this service, but they also assume risks.
Their assets can become unevenly distributed across networks as transaction demand changes. They may need to rebalance inventories, account for price volatility, and manage exposure to bridge or smart contract failures.
If a destination network experiences unusually high demand for withdrawals or swaps, its available inventory could become insufficient. This may result in higher fees, delayed execution, or reduced transaction availability.
The effectiveness of a cross-chain liquidity network consequently depends not only on its software but also on the incentives, capital commitments, risk management practices, and operational reliability of its liquidity providers.
Why More Connected Liquidity Does Not Always Mean Better Liquidity
Connecting multiple blockchain ecosystems can increase users’ access to financial markets, but greater connectivity does not automatically improve every transaction.
The benefits depend on the quality of the available liquidity and the costs associated with accessing it.
A cross-chain route might provide access to a deeper trading pool, yet require several transactions and introduce substantial fees. Another route might be faster but rely on a liquidity provider with limited inventory. A third option might offer a favorable quoted price but involve a less attractive security model.
Users must consider the complete economic outcome.
This includes the expected exchange rate, transaction fees, bridge charges, price impact, execution time, and risks associated with the protocol and asset representation.
Security is especially important. A system that connects many networks may expose users to additional smart contracts, verification mechanisms, validators, or other components. If a critical component fails, the consequences can extend beyond the blockchain where the original transaction began.
Liquidity can also become concentrated in a small number of protocols or providers. Although this concentration may improve execution efficiency under normal conditions, it can create dependencies that become more visible during periods of market stress.
For these reasons, the goal of cross-chain liquidity should not simply be to connect the largest possible number of networks. A more useful objective is to provide reliable, economically efficient, and appropriately secured access to capital across supported ecosystems.
The Role of Cross-Chain Liquidity in a Connected Financial System
The growth of multiple blockchain ecosystems has made liquidity access a central challenge for decentralized finance.
Different networks can support distinct applications, user communities, and financial markets. Yet their usefulness to the broader ecosystem depends partly on whether users can access assets and opportunities without encountering excessive technical or economic barriers.
Cross-chain liquidity seeks to make this access more practical by connecting liquidity sources, facilitating asset exchanges, and coordinating transactions across independent blockchain environments.
Its development requires more than token transfers. It depends on liquidity depth, reliable execution, appropriate asset representations, effective routing, secure interoperability, and sustainable incentives for liquidity providers.
As these systems mature, they may help reduce fragmentation and make decentralized financial services more accessible across blockchain ecosystems. However, their effectiveness will continue to depend on the specific mechanisms used and the risks that users are willing to accept.
Understanding how liquidity is distributed across networks provides the foundation for examining why cross-chain capital movement matters and how different protocols attempt to improve it.
Why Cross-Chain Liquidity Matters
Connecting Capital Across a Fragmented Blockchain Economy
The blockchain industry is no longer built around a single network. Ethereum, Solana, Avalanche, and numerous Layer 2 ecosystems support different applications, financial markets, and user communities. Each network can offer unique advantages, including different transaction costs, processing capabilities, smart contract environments, and decentralized finance opportunities.
However, this expansion creates a fundamental challenge: capital distributed across separate blockchain ecosystems is not automatically accessible everywhere.
A user holding digital assets on one blockchain may want to participate in a lending market on another. A trader might discover a more competitive trading opportunity on a different network, while a decentralized application may want to attract users who hold assets elsewhere. Without effective interoperability and liquidity infrastructure, these activities can require additional transactions, technical knowledge, and expenses.
Cross-chain liquidity matters because it helps connect otherwise fragmented pools of capital, allowing users and applications to access financial opportunities across multiple blockchain ecosystems.
This connectivity can improve how digital assets are utilized, reduce barriers between decentralized markets, and support new financial products. Nevertheless, the benefits depend on the quality of the underlying infrastructure, the availability of liquidity, and the security of the mechanisms connecting the networks.
Understanding why cross-chain liquidity matters requires examining its effects on traders, decentralized finance users, liquidity providers, developers, institutions, and the broader blockchain economy.
1. Improving Access to Decentralized Financial Markets
One of the most important benefits of cross-chain liquidity is improved access to decentralized financial services.
DeFi applications operate across numerous blockchain networks. These applications provide services such as cryptocurrency exchanges, lending and borrowing markets, liquidity pools, derivatives, and automated investment strategies. However, each application may support only a particular selection of networks and assets.
This can limit the usefulness of digital assets held elsewhere.
For example, imagine that a user holds stablecoins on Ethereum but wants to deposit them into a supported lending protocol on another blockchain. If the lending application does not directly accept assets from Ethereum, the user may need to transfer the funds through a compatible cross-chain mechanism before depositing them.
Cross-chain liquidity infrastructure can simplify this process by connecting supported assets and markets across networks.
Depending on the protocol, users may be able to access destination-chain liquidity without manually completing every step of the process. Some systems coordinate transfers and swaps through a single interface, while others require separate transactions or additional confirmations.
Improved access can make decentralized financial services more convenient for users who prefer a particular blockchain but want to participate in opportunities elsewhere.
It can also help emerging ecosystems attract capital from established networks. However, users should evaluate transaction fees, asset compatibility, security assumptions, and destination-market liquidity before moving funds.
Ultimately, cross-chain liquidity can expand access to DeFi, but it does not guarantee that every asset or financial application will be available across every blockchain.
2. Reducing Liquidity Fragmentation
Liquidity fragmentation occurs when capital is distributed across separate markets that cannot efficiently share or access one another’s resources.
In a fragmented blockchain economy, several decentralized exchanges might support the same trading pair while maintaining independent liquidity pools. One exchange could have substantial reserves, whereas another might have limited capital available.
This separation can affect trading efficiency.
Suppose a token has deep liquidity on one blockchain but a relatively small trading pool on another. A trader using the second network might experience greater price impact when buying or selling a large amount of that token.
Moving capital to a market with deeper liquidity could improve the expected execution price. However, the trader must also consider transfer fees, network costs, execution time, and the risks associated with the cross-chain mechanism.
Cross-chain liquidity systems seek to reduce these barriers by connecting users with additional liquidity sources.
Depending on their design, these systems may use destination-chain liquidity providers, cross-chain swaps, aggregated trading routes, or other mechanisms to facilitate transactions across networks.
Better connectivity can help capital reach markets where it is more useful. It may also allow liquidity providers to serve demand from users across multiple ecosystems rather than relying exclusively on activity within a single network.
Nevertheless, liquidity fragmentation cannot always be eliminated. Different markets may have separate assets, pricing mechanisms, settlement requirements, and risk characteristics. Cross-chain infrastructure can improve access, but it cannot create unlimited liquidity or guarantee identical prices across all markets.
3. Improving Trading Opportunities Across Networks
Cryptocurrency traders frequently compare prices, liquidity conditions, and transaction costs across different exchanges and blockchain ecosystems.
When markets operate independently, the same asset may trade at slightly different prices on different platforms. These differences can arise from variations in supply and demand, liquidity depth, market participation, network congestion, and the cost of moving assets.
Cross-chain liquidity can help traders access markets beyond their primary blockchain.
For example, a trader might identify a potentially favorable exchange rate on one network while holding funds on another. A cross-chain trading system may provide a route that combines asset transfers and token swaps to execute the desired transaction.
However, the existence of a price difference does not automatically create a profitable trading opportunity.
The trader must account for all relevant expenses, including trading fees, bridge charges, gas costs, price impact, and possible delays. Prices may also change while a transaction is being processed.
Cross-chain liquidity can be particularly useful for arbitrage strategies, in which traders seek to profit from price differences between markets. These strategies can contribute to price consistency across connected ecosystems when they are executed successfully.
Yet cross-chain arbitrage involves additional execution and settlement risks. A transaction may complete on one network but encounter problems on another, depending on the system’s design. Competition from other traders and automated systems can also reduce potential profits.
For this reason, cross-chain liquidity should be viewed as infrastructure that can expand trading possibilities rather than a guarantee of profitable opportunities.
4. Helping DeFi Applications Reach More Users
Developers building decentralized applications often face a strategic decision about which blockchain ecosystems to support.
Deploying on a single network can simplify development, testing, security reviews, and maintenance. However, it may also limit access to users whose assets and activity are concentrated elsewhere.
Supporting several networks can broaden an application’s reach, but it introduces additional technical and operational requirements.
Each deployment may require separate smart contracts, liquidity arrangements, monitoring systems, and security assessments. Maintaining consistent functionality across multiple environments can become increasingly complex.
Cross-chain liquidity can help address part of this challenge by enabling applications to interact with users and assets originating from other supported networks.
For example, a decentralized exchange may want to provide trading access to users who hold assets on different blockchains. A lending application may seek to attract deposits from multiple ecosystems, while a financial dashboard may aggregate information from several networks.
With appropriate infrastructure, applications can offer cross-chain features without requiring every user to manage all the underlying technical steps independently.
This can improve the potential reach of decentralized services and create opportunities for applications to serve broader markets.
However, cross-chain integration does not remove the need for careful security design. Developers must consider message verification, transaction failures, asset representations, contract permissions, and the possibility of inconsistent states across networks.
The most effective implementations balance wider accessibility with a clear understanding of the additional risks introduced by cross-chain functionality.
5. Making Capital Utilization More Flexible
Capital efficiency describes how effectively financial resources are used to support economic activity.
Within decentralized finance, capital efficiency can be influenced by the amount of liquidity available, the demand for particular assets, the design of financial protocols, and the ability to deploy funds where they are most useful.
When capital is confined to a single blockchain, users may find themselves holding assets in an ecosystem that offers limited opportunities for their intended strategy.
Meanwhile, another network may have stronger demand for those assets or provide a suitable financial application.
Cross-chain liquidity can make capital allocation more flexible by helping users access supported markets across different networks.
For instance, a liquidity provider might compare opportunities on several blockchains before deciding where to deploy assets. A trader may move funds toward a market with better execution conditions, while a decentralized application may seek access to additional liquidity sources.
These choices can improve capital utilization when the expected benefits outweigh the associated costs and risks.
However, moving capital also requires careful evaluation. Transfer expenses, liquidity shortages, smart contract vulnerabilities, and changing market conditions can make an apparently attractive opportunity less beneficial than expected.
Capital efficiency should therefore be evaluated according to the net economic outcome, not simply the number of networks a user can access.
Cross-chain liquidity is most useful when it allows capital to reach suitable opportunities without introducing excessive costs, delays, or security exposure.
6. Supporting the Growth of Emerging Blockchain Ecosystems
New blockchain networks frequently compete to attract developers, users, applications, and liquidity.
An emerging ecosystem may offer low transaction fees, specialized functionality, or incentives for early participants. However, attracting users can be difficult when the network initially has limited liquidity and a small selection of established applications.
This can create a difficult cycle.
Users may hesitate to move to a new blockchain because it lacks sufficient liquidity. Liquidity providers may hesitate to commit capital because there are not enough active users. Developers may then struggle to attract participants because both liquidity and application activity remain limited.
Cross-chain infrastructure can help reduce these barriers by connecting emerging networks with established sources of capital.
Users may be able to transfer supported assets into the new ecosystem, while decentralized applications can potentially attract participants who already hold funds elsewhere.
Liquidity providers may also find opportunities to serve demand in a growing market.
If these connections work effectively, they can support broader participation and help new applications establish themselves.
Nevertheless, cross-chain access alone cannot guarantee sustainable ecosystem growth. Long-term development still depends on application quality, security, user demand, economic incentives, and reliable infrastructure.
An ecosystem that attracts temporary liquidity incentives without building lasting demand may experience significant outflows once those incentives decline.
Cross-chain connectivity can help emerging networks participate in the wider blockchain economy, but durable growth requires more than the ability to move capital into a new environment.
7. Enabling More Flexible Stablecoin Movement
Stablecoins play an important role in decentralized finance because they are designed to maintain a relatively stable value against a reference asset, commonly a fiat currency such as the US dollar.
They are widely used for trading, payments, lending, borrowing, liquidity provision, and managing exposure to cryptocurrency price movements.
However, stablecoin liquidity is distributed across multiple blockchains and platforms.
A particular stablecoin may have deep liquidity on one network but limited availability on another. Different versions of a stablecoin may also have distinct issuance, redemption, and bridging arrangements.
Cross-chain liquidity mechanisms can help users access supported stablecoin markets across networks.
For example, a DeFi participant might hold a supported stablecoin on one blockchain but need it on another to repay a loan, provide liquidity, or execute a trade. A cross-chain transfer or swap can help make the required funds available in the destination ecosystem.
This flexibility can be valuable for decentralized applications that rely on stablecoins for pricing, collateral, and settlement.
However, users must distinguish between native stablecoins and bridged or wrapped representations. These versions may depend on different issuers, custodians, smart contracts, or redemption arrangements.
Cross-chain transfers can also involve additional risks, including bridge failures, liquidity shortages, and temporary differences in market prices.
Stablecoin connectivity is therefore useful only when the destination asset is appropriate for the intended purpose and the transfer mechanism’s risks are understood.
8. Creating Opportunities for Liquidity Providers
Liquidity providers supply capital to markets and protocols that require assets to facilitate trading, lending, borrowing, or other financial activities.
Cross-chain liquidity can expand the range of opportunities available to these participants.
Instead of supplying assets exclusively to one blockchain, providers may be able to support markets across several ecosystems. Depending on the protocol, they might contribute to trading pools, maintain inventory for cross-chain swaps, or provide capital to systems that facilitate asset transfers.
These activities can generate fee income or other incentives.
However, potential returns must be considered alongside the associated risks.
Liquidity providers operating across multiple networks may face inventory imbalances when users demand assets unevenly across destinations. They may need to rebalance funds between chains, manage transaction costs, and monitor changes in market conditions.
They can also be exposed to smart contract vulnerabilities, bridge exploits, asset depegging, and unexpected changes in liquidity demand.
In some liquidity pools, providers face impermanent loss when the relative prices of deposited assets change. Cross-chain arrangements may introduce additional operational or settlement risks, depending on their structure.
Consequently, cross-chain liquidity creates additional opportunities for capital deployment but does not guarantee higher returns.
Successful liquidity provision requires evaluating the protocol’s design, expected transaction activity, fee structure, security assumptions, and the possibility of losses.
9. Supporting Institutional Participation in Digital Asset Markets
Institutional participants often require dependable infrastructure, operational controls, transparent settlement arrangements, and clearly defined risk-management procedures before allocating substantial capital to digital asset markets.
As blockchain-based financial services expand across multiple networks, institutions may encounter liquidity and operational challenges when assets are distributed among separate ecosystems.
For example, a digital asset trading firm might need to manage positions across several blockchains. A financial technology company may want to support blockchain-based payments, while a fund may evaluate decentralized financial opportunities that operate on different networks.
Cross-chain liquidity infrastructure can help these participants access assets and markets across supported ecosystems.
Potential benefits include more flexible capital allocation, access to additional trading venues, and improved coordination between blockchain-based financial applications.
However, institutions must evaluate more than transaction speed and cost.
They may need to consider custody arrangements, counterparty exposure, smart contract security, compliance obligations, settlement finality, asset redemption, and the operational procedures required to manage cross-chain transactions.
Different protocols offer different guarantees. A system relying on a small group of trusted operators presents a different risk profile from one using a decentralized validator network or cryptographic verification mechanisms.
Institutional adoption will therefore depend partly on whether cross-chain infrastructure can meet the reliability, transparency, and control requirements of its intended users.
Cross-chain liquidity may broaden institutional access to digital asset markets, but participation will remain dependent on each institution’s objectives, policies, and assessment of risk.
10. Strengthening the Long-Term Development of Blockchain Interoperability
Blockchain interoperability refers to the ability of different blockchain systems to exchange information, coordinate activities, or support interactions across their separate environments.
Cross-chain liquidity represents an important financial application of this broader concept.
Interoperability can support communication between networks, but financial activity requires additional mechanisms to ensure that assets can be transferred, exchanged, or accessed under appropriate conditions.
For example, a cross-chain messaging protocol may enable one blockchain to communicate information to another. However, that messaging capability alone does not guarantee that the destination network has sufficient liquidity to execute a trade or that a particular asset can be redeemed.
Similarly, a bridge may transfer a token representation between networks without providing deep trading liquidity for that token on the destination chain.
These distinctions demonstrate why interoperability and liquidity must be considered together but should not be treated as identical concepts.
Reliable cross-chain financial activity requires coordination among several components, potentially including messaging systems, verification mechanisms, smart contracts, liquidity providers, and transaction-routing infrastructure.
As these components improve, blockchain applications may become less dependent on isolated liquidity pools and single-network user bases.
However, greater interoperability can also increase system complexity. Each additional integration may introduce new dependencies, security assumptions, and possible failure points.
The long-term challenge is to develop cross-chain infrastructure that combines broad compatibility with reliable execution, appropriate decentralization, and transparent security guarantees.
Conclusion: Cross-Chain Liquidity as a Foundation for Connected Digital Finance
Cross-chain liquidity matters because the blockchain economy is increasingly distributed across multiple networks, each with its own applications, assets, and financial markets.
Without effective connectivity, users may struggle to access suitable markets, developers may face barriers when serving users across ecosystems, and liquidity providers may find it difficult to deploy capital where it is most useful.
Cross-chain infrastructure can help reduce these limitations by connecting liquidity sources, coordinating transactions, and enabling users to access supported assets across blockchain environments.
Its potential benefits include improved DeFi accessibility, more flexible capital allocation, broader trading opportunities, support for emerging ecosystems, and additional options for liquidity providers and institutional participants.
However, these benefits are not automatic. Transaction costs, market depth, execution reliability, asset compatibility, and security risks remain important considerations.
The future of cross-chain liquidity will depend on whether the industry can connect blockchain ecosystems in ways that make capital more accessible without creating unacceptable technical or financial risks.
Understanding these benefits provides a foundation for exploring the mechanisms that make cross-chain activity possible, beginning with the bridges that help assets and their representations move between blockchain networks.
How Blockchain Bridges Move Capital
Understanding the Role of Blockchain Bridges
Blockchain bridges are infrastructure systems designed to facilitate the transfer of digital assets, information, or instructions between separate blockchain networks. They help users access applications and financial markets beyond the blockchain where their assets are originally held.
As the cryptocurrency industry has expanded, blockchain networks have developed different technical architectures, consensus mechanisms, transaction formats, and smart contract environments. These differences mean that an asset recorded on one blockchain cannot ordinarily be transferred directly to another blockchain as though both networks shared a single ledger.
Blockchain bridges address this limitation by coordinating transactions between networks through mechanisms appropriate to their designs.
For example, a user holding a cryptocurrency on Ethereum may want to use that asset in a decentralized finance application operating on an Ethereum Layer 2 network or another compatible blockchain. A bridge can facilitate the movement of the asset or provide a corresponding representation on the destination network.
The exact process depends on the bridge architecture. Some bridges lock assets on the source blockchain and issue corresponding tokens on the destination chain. Others burn tokens on the source chain and mint corresponding tokens on the destination chain. Liquidity-based bridges may instead use available assets on the destination network to fulfill a user’s request.
These mechanisms differ in their security assumptions, liquidity requirements, transaction costs, and settlement procedures.
Blockchain bridges are important to cross-chain liquidity because they help make assets available in ecosystems where users want to trade, lend, borrow, provide liquidity, or interact with decentralized applications.
However, transferring assets does not automatically guarantee that sufficient liquidity exists in the destination market. A successful bridge transaction may deliver tokens to a network where trading depth remains limited.
Understanding how bridges work is therefore essential for evaluating both the opportunities and the risks of cross-chain capital movement.
How a Typical Blockchain Bridge Transaction Works
Although individual bridges use different designs, many cross-chain transactions follow a sequence of common steps.
Step 1: The User Selects the Source and Destination Networks
The process begins when a user chooses the blockchain holding the original asset and the network where the asset is needed.
For example, a user might hold a supported token on Ethereum and want to transfer it to a compatible Layer 2 network.
The user selects the token, the amount, and the destination network through the bridge interface. The system then determines whether the requested transfer is supported and identifies the relevant transaction requirements.
These requirements may include minimum transfer amounts, network fees, estimated processing times, token compatibility, and any restrictions imposed by the protocol.
Users should verify the destination network and token carefully before submitting a transaction. Selecting an incompatible network or an incorrect asset representation can complicate recovery or make funds inaccessible.
Step 2: The Source-Chain Transaction Is Submitted
Once the user confirms the transaction, the wallet submits a transaction to the source blockchain.
Depending on the bridge design, this transaction may deposit assets into a smart contract, transfer them to a designated address, or initiate another protocol-defined process.
The user generally pays the required source-chain transaction fee.
The transaction must then satisfy the relevant confirmation or finality requirements. These requirements vary across blockchains and bridge designs.
A transaction appearing in a block does not necessarily mean that every bridge can immediately treat it as irreversible. Some systems wait for additional confirmations or use other verification mechanisms before processing the next stage.
Step 3: The Bridge Verifies the Source-Chain Event
The bridge must establish that the required event occurred on the source blockchain.
Different systems accomplish this in different ways.
Some rely on validators or operators that observe source-chain transactions and authorize corresponding actions on the destination network. Others use multisignature arrangements, light-client verification, cryptographic proofs, or specialized interoperability infrastructure.
The security of this stage is critical.
If a bridge incorrectly accepts a false message or an invalid source-chain event, an attacker might be able to initiate unauthorized asset releases or token issuance on the destination chain.
The verification mechanism therefore forms a central part of the bridge’s security model.
Step 4: The Destination Network Processes the Transfer
After the source-chain event has been accepted, the bridge initiates the corresponding destination-chain action.
Depending on the architecture, this may involve minting a representation of the original asset, releasing assets held in a destination-side liquidity pool, or completing another transfer process.
For example, a lock-and-mint bridge may issue a corresponding token on the destination chain after the source asset has been securely locked.
A liquidity-based bridge may instead transfer an existing destination-chain asset from a liquidity provider’s inventory.
These approaches can produce similar user experiences, but their underlying mechanisms and risk exposures differ.
Step 5: The User Receives the Destination Asset
The process concludes when the destination-chain transaction is completed and the relevant asset becomes available to the user.
The user may then interact with supported decentralized applications, exchange the token, provide liquidity, or use it in another permitted activity.
However, the asset received may not always be identical in technical or economic terms to the original asset.
It could be a wrapped representation, a bridged version of a token, or a native destination-chain asset delivered through a liquidity-based mechanism.
Users should confirm which asset they receive, how it is supported, and whether any redemption or withdrawal restrictions apply.
This distinction is particularly important when a destination blockchain supports several versions of a token with similar names.
Lock-and-Mint Bridges: Creating Asset Representations
One widely used bridge design is the lock-and-mint model.
In this arrangement, a bridge locks the original asset on the source blockchain and issues a corresponding token on the destination blockchain. The destination token is intended to represent the value or claim associated with the locked asset, subject to the bridge’s design and security assumptions.
Consider a hypothetical example involving a user who wants to move 100 units of a supported token from Blockchain A to Blockchain B.
The user deposits the tokens into the bridge’s designated smart contract on Blockchain A. Once the deposit is verified, the bridge authorizes the issuance of the corresponding token on Blockchain B.
The user receives the destination representation and can use it in supported applications on that network.
In a properly functioning design, the bridge maintains rules intended to prevent unauthorized issuance and ensure that the amount of destination tokens corresponds to the assets secured on the source chain.
When the user wants to return to Blockchain A, the reverse process may involve burning the destination tokens and releasing the original assets from the source-chain contract.
The exact implementation varies between protocols.
Advantages of Lock-and-Mint Bridges
This design can provide a straightforward method for representing assets across blockchain environments.
It can also support the use of an asset on a destination chain without requiring every destination transaction to access the original blockchain.
Once issued, the destination token can potentially interact with compatible decentralized exchanges, lending applications, and liquidity pools.
Limitations and Risks
The destination token depends on the bridge’s ability to maintain the relationship between the representation and the underlying asset.
If the bridge’s verification or authorization mechanisms are compromised, an attacker might issue unauthorized tokens or release assets improperly.
The destination representation may also experience reduced liquidity if users lose confidence in the bridge or if market participants question its redemption guarantees.
Consequently, a wrapped or bridged token’s market value may diverge from that of the original asset.
Users should understand the specific bridge mechanism and avoid assuming that all token representations have equivalent security or redemption properties.
Burn-and-Mint Bridges: Issuing Tokens Across Networks
Burn-and-mint bridges use a different mechanism to transfer supported assets between blockchain networks.
Instead of locking the original tokens and issuing a separate representation, the system burns tokens on the source chain and authorizes the creation of corresponding tokens on the destination chain.
Burning generally means that the tokens are permanently removed from the relevant token supply according to the protocol’s rules.
For example, a supported token issuer may authorize a token to operate on several blockchain networks. When a user transfers tokens from one supported network to another, the source tokens are burned and an equivalent amount is minted on the destination network after the transfer is properly verified.
This arrangement can help maintain a consistent token supply across supported networks.
However, it depends on the token’s issuance model and the authorization mechanisms controlling the burn-and-mint process.
Potential Benefits
Burn-and-mint systems can avoid maintaining separate locked reserves for every cross-chain transfer, depending on their design.
They may also simplify supply accounting for tokens that are natively issued across several supported networks under a common authorization framework.
For users, the experience can resemble a direct transfer even though the underlying process involves separate transactions on different blockchains.
Important Considerations
Not every cryptocurrency supports burn-and-mint transfers. The mechanism generally requires token contracts and authorization systems designed for this purpose.
The security of the process depends on the controls governing token burning and issuance, as well as the mechanisms that verify cross-chain events.
If an attacker gains unauthorized minting privileges or compromises the verification process, the token’s supply and economic integrity could be affected.
Users should therefore distinguish between a token issuer’s officially supported cross-chain transfer mechanism and a third-party bridge that creates an independent wrapped representation.
The two arrangements may provide similar functionality while relying on different trust assumptions.
Liquidity-Based Bridges: Moving Capital Through Available Reserves
Liquidity-based bridges use assets already available on the destination network to fulfill cross-chain transfers.
Rather than requiring every transfer to follow a lock-and-mint process, these systems may allow a user to deposit an asset on one blockchain and receive a supported asset from a liquidity provider on another.
The bridge or protocol coordinates the transaction and manages the corresponding settlement or inventory adjustments.
Consider a hypothetical example.
A user holds a supported stablecoin on Blockchain A but wants the same type of stablecoin on Blockchain B.
A liquidity-based bridge may receive the user’s deposit on Blockchain A and deliver stablecoins from a liquidity provider’s available inventory on Blockchain B.
The user receives the destination asset once the relevant execution conditions are satisfied.
The liquidity provider may subsequently rebalance its positions or receive settlement according to the protocol’s design.
Why Destination-Side Liquidity Matters
The efficiency of this process depends heavily on the assets available on the destination network.
If the liquidity provider maintains sufficient reserves, the transfer may complete without requiring the user to wait for the conventional issuance of a wrapped representation.
However, if destination-side reserves are limited, the bridge may impose higher fees, restrict the transfer amount, delay execution, or fail to provide a suitable route.
Liquidity-based bridges therefore depend on both technical coordination and effective liquidity management.
Risks for Liquidity Providers
Providers must maintain appropriate inventories across supported networks and manage changes in demand.
For example, unusually high demand for transfers into one blockchain may deplete its available reserves. The provider may then need to move capital from another network or wait for additional liquidity to become available.
Rebalancing creates costs and may introduce operational complexity.
Providers also face risks associated with smart contracts, settlement failures, token price movements, and the security of the infrastructure used to coordinate transfers.
Liquidity-based designs can improve the user experience, but they do not eliminate the risks associated with cross-chain transactions.
How Blockchain Bridges Support Cross-Chain DeFi
Blockchain bridges are particularly important for decentralized finance because DeFi applications depend on the availability of assets within specific execution environments.
A user might hold cryptocurrency on one blockchain but want to use it as collateral on another. A trader may wish to access a decentralized exchange with deeper liquidity, while a liquidity provider might want to supply assets to a pool operating on a different network.
Bridges can help make these activities possible by transferring assets or providing supported destination-chain representations.
For example, a user could transfer an eligible asset to a blockchain that hosts a lending protocol. Once the asset is available and accepted by the application, the user may be able to deposit it as collateral or use it for another supported financial activity.
Similarly, traders can use bridging infrastructure to reach markets that are not directly accessible from their original network.
However, the availability of a bridge does not guarantee that a destination application will accept the transferred token. The application must support the specific asset contract and its relevant properties.
A lending protocol may accept one version of a stablecoin but reject another. A decentralized exchange may support a wrapped token while maintaining a separate pool for the native asset.
Users must therefore verify compatibility before transferring funds.
Bridges can connect blockchain environments, but applications still determine which assets they accept and under what conditions.
Transaction Speed, Fees, and Finality
Bridge performance is an important consideration when moving capital across blockchain ecosystems.
Users generally want transfers to complete quickly and at a reasonable cost. However, cross-chain transactions often involve several independent processes, and each can affect the final outcome.
Source-Chain Fees
The initial transaction usually requires a fee on the source blockchain.
The amount depends on the network’s fee model, transaction complexity, and current demand for block space.
During periods of congestion, source-chain fees may rise, making smaller transfers less economical.
Destination-Chain Fees
Some bridge designs require an additional destination-chain transaction, such as minting a token or completing a withdrawal.
Depending on the protocol, the user, bridge operator, relayer, or another participant may cover or account for this expense.
Users should examine the complete fee structure rather than assuming that a quoted bridge fee includes every relevant cost.
Confirmation and Finality Requirements
Different blockchain networks have different transaction confirmation and finality characteristics.
A bridge may wait for a specified number of confirmations, verify a cryptographic proof, or rely on another mechanism before accepting a source-chain event.
These safeguards can increase the time required for a transfer but are important to the bridge’s security model.
Reducing confirmation requirements without an appropriate security mechanism can expose a bridge to risks associated with reorganizations or invalid source-chain assumptions.
Destination Execution
After verification, the destination transaction must be processed by the relevant network.
Network congestion, insufficient liquidity, failed transactions, or protocol-specific restrictions can affect completion time.
A transfer that appears straightforward in a user interface may therefore depend on several underlying systems working correctly.
Reliable bridge infrastructure must balance speed, cost, and security rather than optimizing for transaction speed alone.
The Security Risks of Blockchain Bridges
Blockchain bridges can connect financial markets, but they also introduce security considerations that users must understand.
Because bridges coordinate activity between separate networks, their designs often include additional smart contracts, verification mechanisms, operators, or liquidity arrangements.
A vulnerability in a critical component can affect the assets or transactions that depend on it.
Smart Contract Vulnerabilities
Bridge contracts may contain bugs involving access controls, transaction validation, token accounting, or withdrawal authorization.
If an attacker exploits a vulnerability, the consequences could include unauthorized transfers, asset losses, or disruption of bridge operations.
Independent security reviews and careful contract design can help reduce these risks, but audits do not guarantee that a protocol is free from vulnerabilities.
Verification and Validator Risks
Some bridges rely on validators, signers, or operators to confirm events and authorize destination-chain transactions.
If the required participants collude, are compromised, or fail to follow the protocol’s rules, the bridge may accept unauthorized messages or release assets incorrectly.
The security implications depend on the number of participants, their independence, the threshold required to authorize transactions, and the mechanisms used to detect or prevent misconduct.
Liquidity and Redemption Risks
A bridged token may lose liquidity or become difficult to redeem if the bridge experiences an exploit, operational failure, or loss of user confidence.
Even when the destination token remains transferable, users may discover that the underlying redemption process is unavailable or unreliable.
This can cause the token to trade below the value of its intended underlying asset.
Operational and Network Risks
Cross-chain systems depend on infrastructure that must operate across different blockchain environments.
Network congestion, relayer failures, software errors, or disruptions affecting one of the connected networks may delay or prevent transactions.
Users should understand the recovery procedures and withdrawal options available if a bridge becomes temporarily unavailable.
Concentration Risk
A protocol may support many blockchains while relying on a small number of critical components or operators.
This creates a potential concentration of risk. If a central verification service, administrative key, or important contract is compromised, several connected networks may be affected.
The number of supported blockchains alone is therefore not a reliable measure of bridge security.
How Users Can Evaluate a Blockchain Bridge
Before transferring significant assets, users should evaluate the bridge’s design, operational history, and security assumptions.
Important considerations include:
- Bridge architecture: Determine whether the system uses locking and minting, burning and minting, liquidity-based transfers, or another mechanism.
- Verification model: Understand how the bridge verifies transactions and authorizes actions on the destination network.
- Security reviews: Look for credible independent audits, published security documentation, and information about how identified vulnerabilities were addressed.
- Liquidity availability: Check whether sufficient destination-side liquidity exists for the intended transfer or subsequent transaction.
- Asset compatibility: Confirm that the destination application accepts the exact token representation being transferred.
- Fees and execution estimates: Review the total expected costs, minimum transfer requirements, and estimated completion time.
- Withdrawal arrangements: Understand how assets can be returned to the original network and what conditions may affect withdrawals.
- Emergency controls: Examine whether the protocol can pause transactions, who controls administrative permissions, and how incidents are handled.
- Track record: Review relevant incidents and the protocol’s response, while recognizing that a history without known exploits does not prove that a bridge is secure.
Users should also consider transaction size and avoid assuming that a bridge’s interface or popularity guarantees the safety of deposited assets.
A careful assessment can help identify risks, but no evaluation method can eliminate all uncertainty in cross-chain transactions.
The Future of Blockchain Bridges and Cross-Chain Capital Movement
Blockchain bridge infrastructure continues to evolve as developers explore ways to improve interoperability, transaction execution, verification, and liquidity access.
Some systems focus on simplifying transfers between networks. Others emphasize cryptographic verification, specialized messaging infrastructure, liquidity routing, or improved coordination between applications.
These approaches may increasingly work together, allowing users to access cross-chain services through interfaces that hide some of the technical complexity.
However, a simpler user experience should not be confused with a simpler underlying security model. A single transaction initiated through an application may still depend on multiple contracts, networks, validators, and liquidity sources.
The long-term development of bridge infrastructure will depend on whether protocols can provide reliable asset movement while making their security assumptions understandable and their failure modes manageable.
Greater standardization and more effective interoperability may improve connectivity between blockchain ecosystems. At the same time, users and developers will need to continue evaluating the risks associated with cross-chain dependencies.
Ultimately, blockchain bridges are an important part of the infrastructure that allows capital to move between independent networks. Their contribution to cross-chain liquidity depends on how securely and efficiently they connect users with the assets and financial services they need.
Understanding bridge architecture provides the foundation for examining the next major component of cross-chain finance: the liquidity pools and decentralized exchanges that help users trade assets across blockchain ecosystems.
Cross-Chain Liquidity Pools and Decentralized Exchanges
Understanding Cross-Chain Liquidity Pools
Liquidity pools are an essential component of decentralized finance because they provide the assets needed to facilitate cryptocurrency trading and other financial activities. When these pools operate across connected blockchain ecosystems, they can help users access liquidity beyond the network where their assets are originally held.
A traditional decentralized exchange may maintain a liquidity pool on a single blockchain. Users interact with a smart contract to exchange supported tokens, while liquidity providers supply the assets required for these transactions.
However, the expansion of blockchain technology has created a more complicated environment. Ethereum, Solana, Avalanche, and multiple Layer 2 networks support independent applications and trading markets. As a result, liquidity can become distributed across different ecosystems, making it difficult for users to access the most suitable market from a single location.
Cross-chain liquidity pools and related trading systems aim to reduce this fragmentation.
Depending on the protocol, a cross-chain trading system may coordinate liquidity pools on several networks, use destination-chain liquidity providers, or combine separate transactions into a single user-facing operation.
For example, a user holding a supported cryptocurrency on one blockchain may want to exchange it for a stablecoin on another network. A cross-chain system could coordinate the transfer and exchange through available liquidity sources, allowing the user to receive the destination asset without manually managing every underlying step.
The process does not necessarily mean that a single liquidity pool physically spans multiple blockchains. In many implementations, separate pools remain on their respective networks while interoperability infrastructure coordinates the transactions between them.
The central objective is to make liquidity distributed across blockchain ecosystems more accessible and useful to participants in decentralized finance.
Achieving this objective requires effective coordination, sufficient liquidity, appropriate asset compatibility, and reliable security mechanisms.
How Traditional Decentralized Exchanges Use Liquidity Pools
To understand cross-chain decentralized exchanges, it is important to examine how conventional decentralized exchanges operate.
A decentralized exchange, commonly known as a DEX, enables users to trade supported digital assets through blockchain-based smart contracts. Unlike a centralized exchange, a DEX can allow users to interact directly with the protocol using their own wallets rather than depositing funds into a conventional exchange account.
Many DEXs use automated market makers, or AMMs, to facilitate trading.
An AMM uses a mathematical pricing mechanism and the assets available in a liquidity pool to determine how trades are executed. Liquidity providers deposit supported tokens into the pool, and traders exchange those assets according to the protocol’s rules.
Consider a hypothetical pool containing ETH and a stablecoin. A trader can exchange ETH for the stablecoin or exchange the stablecoin for ETH. Each transaction changes the pool’s asset balances, which can influence the exchange rate.
In a constant-product AMM, for example, the relationship between the quantities of two assets is commonly represented by the equation:
x × y = k
In this simplified model, x and y represent the quantities of the two assets in the pool, while k represents a constant maintained by the pricing mechanism, excluding the effects of fees and other implementation details.
When a trader purchases one asset from the pool, its available quantity decreases while the quantity of the other asset increases. This changes the effective exchange rate.
The larger the transaction relative to the pool’s available liquidity, the greater the potential price impact.
This model is useful for understanding many AMMs, although not every decentralized exchange uses a constant-product formula. Some use concentrated liquidity, different pricing curves, or order-book-based mechanisms.
Traditional DEXs provide the foundation for cross-chain trading, but their liquidity pools generally operate within the blockchain environment where they are deployed.
Additional infrastructure is needed to coordinate trading activity across separate networks.
Why Cross-Chain Decentralized Exchanges Are Different
A cross-chain decentralized exchange helps users exchange assets that exist on different blockchain networks.
For example, a trader might hold a token on Ethereum and want to receive another token on Solana. Because the two blockchains maintain separate transaction environments and asset records, the exchange cannot ordinarily be completed through a single conventional liquidity pool shared directly by both networks.
A cross-chain trading system must coordinate the necessary operations.
Depending on its architecture, it may use a bridge to transfer assets, a liquidity provider to deliver tokens on the destination network, or a routing system that combines several swaps and transfers.
The system must also account for differences in token standards, network fees, transaction confirmation requirements, and destination-chain liquidity.
This introduces additional complexity compared with a swap that occurs entirely on one blockchain.
A conventional DEX transaction generally involves interaction with contracts on one network. A cross-chain transaction may depend on several networks, smart contracts, verification mechanisms, and liquidity sources.
These dependencies affect execution time, security assumptions, and the possibility of partial failure.
For users, the goal of a cross-chain DEX is to simplify this complexity while providing a competitive execution price and a reliable transaction process.
However, not all cross-chain exchanges use the same architecture. Some provide integrated interfaces for bridging and swapping, while others use liquidity networks or specialized cross-chain execution protocols.
Understanding the underlying design is important when evaluating the costs and risks of a particular service.
How Cross-Chain Swaps Work
A cross-chain swap allows a user to exchange an asset on one blockchain for an asset on another blockchain.
Although implementations differ, a typical process involves several stages.
Stage 1: Selecting the Assets and Networks
The user chooses the source asset, source blockchain, destination asset, and destination blockchain.
For example, the user may want to exchange a supported token on Blockchain A for a stablecoin on Blockchain B.
The trading interface identifies available routes and estimates the expected output, transaction costs, and execution time.
These estimates depend on current prices, available liquidity, network conditions, and the protocol’s routing mechanism.
Stage 2: Finding an Appropriate Route
The system evaluates available liquidity sources and identifies a route that can fulfill the request.
A route may involve a direct swap, an intermediate token, a bridge, a destination-side liquidity provider, or a combination of these components.
For example, the system might exchange the source token for a widely supported intermediary asset before arranging the destination-side exchange.
The most suitable route depends on the total economic outcome rather than the quoted exchange rate alone.
A route offering a favorable price may involve higher bridge fees or greater price impact. Another route may cost less but require additional execution steps.
Stage 3: Executing the Source-Side Transaction
Once the user approves the transaction, the source-side operation is submitted to the relevant blockchain.
Depending on the protocol, the user may need to approve a token allowance, deposit assets into a smart contract, or authorize another transaction.
The transaction must satisfy the protocol’s requirements before the cross-chain process can continue.
Stage 4: Coordinating Cross-Chain Execution
The protocol then coordinates the required actions between the source and destination networks.
This stage may involve verifying the source transaction, sending a cross-chain message, arranging settlement, or coordinating a liquidity provider.
Some systems depend on destination-side liquidity, while others use asset representations or other mechanisms.
The exact process determines how the protocol handles transaction failures and whether the operations can be completed atomically or require separate settlement steps.
Stage 5: Delivering the Destination Asset
The destination-side operation completes, and the user receives the requested asset if execution succeeds.
The final amount may differ from the initial estimate because of market movements, fees, price impact, or other execution conditions, depending on the protocol’s protections.
Users should review the expected output, slippage tolerance, minimum received amount, and any available recovery procedures before initiating a transaction.
A cross-chain swap can reduce the need to manage several separate operations manually, but it does not eliminate the technical dependencies involved in executing transactions across different blockchains.
The Role of Liquidity Aggregators
Liquidity aggregators help users identify and access liquidity across multiple trading venues.
Within a single blockchain, an aggregator may compare prices across decentralized exchanges and divide a trade among different pools to seek a better overall execution result.
Cross-chain aggregators extend this concept by considering routes involving more than one blockchain.
Depending on their capabilities, they may compare supported networks, trading pools, bridge routes, liquidity providers, and transaction fees.
Suppose a user wants to exchange a token on one network for a stablecoin on another. A cross-chain aggregator might evaluate several possible paths:
- A direct cross-chain swap through a supported liquidity network.
- A bridge transfer followed by a destination-chain swap.
- A route that exchanges the original asset for an intermediary token before transferring it.
- A route that uses a different bridge or destination-side liquidity source.
The aggregator attempts to identify a route that meets the user’s requirements.
However, the lowest quoted fee does not always represent the best outcome. Execution reliability, security assumptions, expected price impact, processing time, and the quality of the destination asset must also be considered.
Furthermore, an aggregator cannot guarantee access to liquidity that does not exist. Its performance depends on the markets and protocols available to it.
Users should also understand that aggregation does not necessarily remove the risks of the underlying bridges or decentralized exchanges. It may simplify access while retaining dependencies on the protocols used to complete the transaction.
Concentrated Liquidity and Its Cross-Chain Implications
Some modern decentralized exchanges use concentrated liquidity models rather than distributing capital uniformly across an entire possible price range.
In a concentrated liquidity design, liquidity providers can allocate their assets within selected price ranges. This can improve capital efficiency when trading activity occurs within those ranges.
For example, a liquidity provider may choose to supply liquidity within a narrow price interval for a stablecoin trading pair. If the market price remains inside that interval, the capital may support trades more efficiently than a comparable amount distributed across a much wider range.
However, concentrated liquidity introduces additional considerations.
If the market price moves outside a provider’s selected range, that position may stop contributing active liquidity until the price returns or the provider adjusts the position.
When a decentralized exchange operates on one blockchain, these conditions are evaluated within that market’s own environment.
In cross-chain trading, liquidity aggregators may need to consider the available depth and pricing conditions of pools deployed on different networks.
A pool that appears large in total value may provide limited liquidity at the price relevant to a particular trade. Similarly, liquidity available on one blockchain cannot automatically satisfy a trade on another unless the routing system can access it through an appropriate mechanism.
Consequently, cross-chain routing requires more than comparing the total value locked across several networks.
It must evaluate the liquidity actually available for the intended transaction, including price ranges, trading fees, transfer costs, and the reliability of the cross-chain execution path.
How Liquidity Providers Support Cross-Chain Exchanges
Liquidity providers supply the assets that enable trading and asset delivery.
In conventional decentralized exchanges, providers typically deposit tokens into liquidity pools and earn a share of trading fees or other protocol incentives.
In cross-chain systems, providers may maintain inventory on several blockchains or participate in networks designed to facilitate cross-chain swaps.
For example, a provider may maintain stablecoins on Blockchain B while users initiate transactions from Blockchain A.
When a cross-chain swap is requested, the system may use the provider’s destination-side inventory to deliver the required stablecoin. A separate process then coordinates the provider’s settlement or inventory management.
This can make cross-chain execution more convenient because the destination asset may already be available.
However, providers must maintain sufficient capital on the networks where demand occurs.
If many users request transfers into one ecosystem, its available inventory may decline. The provider may need to rebalance funds, obtain additional capital, or adjust fees to reflect changing conditions.
These operations introduce costs and risks.
Providers must also consider whether the assets on different networks have equivalent redemption properties, whether a bridge or settlement mechanism is dependable, and how the system handles incomplete transactions.
Cross-chain liquidity provision can create additional revenue opportunities, but profitability depends on actual trading activity, fee income, rebalancing costs, capital efficiency, and the possibility of losses.
Slippage and Price Impact in Cross-Chain Trading
Slippage is an important consideration when trading digital assets, particularly when transactions involve several liquidity sources or blockchain networks.
It generally refers to the difference between the expected execution price and the price ultimately obtained. Market movement between quoting and execution can contribute to slippage, while price impact describes the effect of the trade itself on the market price.
These concepts are related but not identical.
A transaction involving several pools may experience price impact at multiple stages. If it also involves a bridge or destination-side liquidity provider, the total economic outcome may depend on additional fees and execution conditions.
For example, a user might receive an attractive initial quote for exchanging a cryptocurrency on Blockchain A into a stablecoin on Blockchain B. However, the transaction could become less favorable if the source token’s price changes, available destination liquidity declines, or the route incurs unexpected costs.
Many trading interfaces allow users to set a slippage tolerance or specify a minimum acceptable output.
These controls can help limit execution at an unfavorable price, but they do not guarantee that a transaction will succeed. A stricter tolerance may cause a transaction to fail if market conditions change before execution.
Users should therefore compare the expected output with the total amount they are willing to spend, taking account of all relevant fees and risks.
A cross-chain aggregator can help estimate these costs, but its quoted result should be treated as an estimate subject to the protocol’s execution rules.
Managing Failed or Delayed Cross-Chain Swaps
Cross-chain swaps involve several components that may operate independently. This creates situations in which one stage succeeds while another encounters a problem.
For example, a source-chain transaction may be confirmed, but the destination transaction might be delayed because of network congestion, insufficient liquidity, or a problem with the cross-chain messaging process.
The appropriate recovery procedure depends on the protocol.
Some systems provide transaction tracking, automatic retries, refunds, or mechanisms for recovering assets after a failed operation. Others require users to follow specific recovery instructions or wait for the relevant settlement process to finish.
It is important not to assume that every cross-chain transaction can be reversed immediately.
A source-chain transaction may already be final even when the destination-side operation remains incomplete. Recovery might depend on the bridge’s design, the status of the cross-chain message, and the permissions available to the protocol’s operators or smart contracts.
Users should retain transaction identifiers, monitor the official transaction status, and follow the protocol’s documented recovery process when a transfer appears delayed.
They should also be cautious of individuals claiming they can recover funds through unofficial services, especially if they request wallet seed phrases, private keys, or additional payments without a verifiable basis.
Reliable cross-chain systems should communicate transaction status clearly and explain what happens when individual stages fail.
Security Considerations for Cross-Chain Liquidity Pools and DEXs
Cross-chain trading introduces risks that can extend beyond the liquidity pool used for the final swap.
A system may depend on bridge contracts, messaging infrastructure, token issuers, liquidity providers, and destination-chain execution mechanisms.
A vulnerability in any critical component can affect the overall transaction.
Smart contract exploits may allow unauthorized asset movements or manipulation of liquidity arrangements. Compromised verification systems can cause a protocol to accept invalid cross-chain instructions. Insufficient liquidity may also prevent users from completing a transaction at the expected price.
There are additional risks associated with token representations.
A wrapped or bridged token may depend on an underlying asset held elsewhere. If the mechanism supporting redemption fails, the token’s market price or liquidity may deteriorate.
Users should therefore evaluate the security of the entire route rather than focusing only on the reputation of the decentralized exchange interface.
Important considerations include the bridge’s verification model, the permissions associated with smart contracts, the quality of available liquidity, the protocol’s history of incidents, and the mechanisms available for handling failed transactions.
Security reviews and audits can provide useful information, but they do not eliminate all risk.
Cross-chain trading systems must also manage operational complexity, because problems can arise when multiple networks or protocol components behave differently from expected.
The Future of Cross-Chain Liquidity Pools and Decentralized Exchanges
Cross-chain liquidity pools and decentralized exchanges are part of a broader effort to make blockchain-based financial services more accessible across independent networks.
As the industry develops, trading systems may improve their ability to identify suitable routes, compare execution costs, and coordinate asset delivery across multiple ecosystems.
Better routing can potentially help users access more competitive markets, while improved liquidity management may reduce the frequency of failed or expensive transactions.
Developers may also continue to simplify the user experience by integrating bridging, swapping, and transaction monitoring into unified interfaces.
However, the long-term success of these systems will depend on more than convenience.
They must provide dependable execution, maintain appropriate security controls, support transparent pricing, and handle liquidity shortages and transaction failures effectively.
Greater integration may also create new dependencies between protocols. If several applications rely on the same bridge or liquidity network, a failure in that infrastructure could affect many users simultaneously.
For this reason, cross-chain trading infrastructure must balance connectivity with resilience and clear risk management.
The objective is not simply to connect more exchanges or blockchains. It is to enable users to access suitable liquidity across networks while maintaining reasonable costs, reliable execution, and an appropriate understanding of the associated risks.
Conclusion
Cross-chain liquidity pools and decentralized exchanges help connect financial markets that would otherwise remain separated by blockchain boundaries.
Through liquidity providers, automated market makers, routing systems, and cross-chain execution mechanisms, users can access supported assets and trading opportunities across multiple networks.
These systems can improve market accessibility and make capital allocation more flexible, but their effectiveness depends on available liquidity, execution costs, asset compatibility, and the reliability of the underlying infrastructure.
Cross-chain exchanges also introduce additional complexity. Users must account for slippage, transaction delays, smart contract vulnerabilities, bridge security, and the possibility of incomplete transactions.
Understanding these factors is essential when evaluating cross-chain trading opportunities.
As blockchain ecosystems become increasingly interconnected, liquidity pools and decentralized exchanges will remain important components of the infrastructure supporting cross-chain capital movement.
Atomic Swaps and Cross-Chain Transactions
What Are Atomic Swaps?
Atomic swaps are a method of exchanging digital assets across different blockchain networks without requiring both assets to be traded through a conventional centralized exchange. They are designed to let two parties exchange cryptocurrencies under predefined conditions, reducing the risk that one party transfers an asset while the other fails to deliver the agreed asset.
The term atomic refers to the all-or-nothing nature of the exchange. In a properly designed atomic swap, either the required conditions are fulfilled and the exchange completes, or the transaction does not complete as intended. This principle can help reduce counterparty risk, although the actual level of protection depends on the specific protocol, blockchain capabilities, and transaction design.
For example, imagine a user holds Bitcoin but wants to receive a cryptocurrency on another compatible blockchain. Instead of selling Bitcoin through a centralized exchange and then purchasing the second asset, the user may be able to participate in a cross-chain exchange using an atomic-swap mechanism.
Atomic swaps are an important concept in cross-chain liquidity because they provide a way to exchange assets across blockchain environments while reducing dependence on certain intermediaries.
However, atomic swaps are not a universal solution. They may require compatible cryptographic features, appropriate transaction conditions, and sufficient technical support on the participating networks. Their practical use also depends on the assets involved, transaction costs, liquidity availability, and the experience of the user.
How Atomic Swaps Work
One well-known approach to atomic swaps uses a mechanism called a Hash Time-Locked Contract (HTLC). An HTLC combines a cryptographic hash condition with a time limit to coordinate an exchange between parties operating on different blockchains.
The process generally involves several stages.
1. The parties agree on the exchange.
Two participants agree on which assets they will exchange, the quantities involved, and the conditions under which the transaction should proceed. Both parties need to understand the relevant transaction fees, time limits, and possible failure scenarios.
2. A cryptographic secret is established.
One participant generates a secret value and calculates its cryptographic hash. The hash can be shared publicly without revealing the original secret. The secret itself becomes an important part of the exchange process.
3. Conditional transactions are created.
The participants establish transactions or contracts on their respective blockchains. These arrangements specify the conditions for claiming the assets. In an HTLC-based design, a participant may claim the other party’s funds by revealing the secret associated with the agreed hash.
4. The exchange progresses across both networks.
When the required conditions are met, the participants claim the assets according to the protocol’s rules. The revelation of the secret on one blockchain can provide the information needed to complete the corresponding transaction on the other blockchain.
5. Time limits provide a recovery mechanism.
If the exchange does not complete within the specified period, the time-lock conditions can allow funds to be refunded to their original owners. The precise refund process depends on the implementation, and participants must follow the required steps correctly.
The purpose of this design is to coordinate an exchange without requiring both parties to rely solely on the promise of a centralized intermediary.
Nevertheless, HTLC-based swaps introduce operational requirements. Participants must monitor the transactions, account for differences in confirmation times, and understand how refunds work. Poorly chosen time limits or user mistakes can create additional complications.
Atomic Swaps Versus Blockchain Bridges
Atomic swaps and blockchain bridges both help assets move between blockchain ecosystems, but they solve different problems.
A bridge generally provides infrastructure for transferring or representing assets across networks. Depending on its architecture, it may lock assets on one chain and issue corresponding tokens on another, burn and mint tokens, or use a liquidity-based mechanism to deliver assets on the destination network.
An atomic swap, by contrast, focuses on exchanging one asset for another under coordinated conditions. It does not necessarily require a wrapped representation of the original asset, although the exact outcome depends on the assets and protocol involved.
Consider a user who wants to exchange a native asset on one blockchain for a native asset on another. A bridge-based workflow might first transfer or represent the original asset on the destination network before the user trades it. An atomic swap may allow the two assets to be exchanged directly through compatible conditional transactions.
The distinction is important because transferring an asset and exchanging an asset are not the same operation. Some cross-chain applications combine bridging, swapping, liquidity routing, and other services into a single user experience.
Neither approach is automatically safer or more efficient in every situation. A bridge may offer broader network support and a simpler user experience, while an atomic swap may reduce reliance on particular custodial or liquidity-intermediation arrangements. The most suitable option depends on the protocol’s security model, supported assets, costs, speed, and recovery procedures.
Atomic Swaps and Cross-Chain Liquidity
Atomic swaps can contribute to cross-chain liquidity by enabling direct exchanges between assets that exist on separate blockchain networks. Instead of requiring users to move through a centralized exchange, an appropriately designed protocol can coordinate transactions between participating networks.
This can be useful in several ways.
First, atomic swaps may expand trading options for users who hold assets on different blockchains. When a compatible swap mechanism supports the required assets, users may gain another way to exchange value across ecosystems.
Second, atomic swaps can reduce dependence on certain intermediaries. Depending on the design, users may retain control of their funds while the exchange conditions are being fulfilled. However, this does not eliminate every trust assumption, and users still need to assess the software, contracts, wallets, and networks involved.
Third, atomic swaps can support the broader development of decentralized trading infrastructure. They demonstrate how separate blockchain systems can coordinate conditional transactions without necessarily sharing the same execution environment.
There are also important limitations. Atomic swaps do not automatically create deep liquidity. A protocol may support an exchange technically but still have few participants willing to trade the required assets. Limited market depth can make a trade difficult, expensive, or impractical.
This means that cross-chain liquidity depends on more than transaction coordination. Successful exchanges also require available counterparties, competitive pricing, suitable transaction costs, and reliable mechanisms for handling failed transactions.
Challenges and Limitations of Atomic Swaps
Despite their advantages, atomic swaps face several technical and practical challenges.
Blockchain compatibility: Not every blockchain supports the same scripting capabilities, cryptographic operations, or transaction conditions. Some networks may not support the mechanisms required for a particular atomic-swap design.
Liquidity availability: Atomic swaps need participants willing to exchange the relevant assets. A technically functional protocol cannot guarantee that a suitable trading partner or competitive price will always be available.
Transaction costs: Users may need to pay network fees on both blockchains. If one network becomes congested or transaction fees increase, the overall cost of completing the exchange may become unattractive.
Execution timing: Different blockchains have different confirmation times and finality characteristics. A transaction that takes longer than expected can complicate the coordination process, especially when time-locked conditions are involved.
User experience: Some atomic-swap processes require users to understand transaction states, secrets, refund conditions, and network-specific procedures. These requirements can make the experience more complicated than using a conventional trading interface.
Security and implementation risks: Cryptographic conditions can provide valuable safeguards, but incorrect implementations, vulnerable software, wallet mistakes, and inadequate operational procedures may still create risks.
Limited flexibility: Some atomic-swap designs work best with specific assets and compatible blockchain features. This can limit their applicability compared with cross-chain platforms that support many networks through broader infrastructure.
These limitations help explain why atomic swaps are one component of the cross-chain ecosystem rather than a complete replacement for bridges, liquidity pools, and interoperability protocols.
The Future of Atomic Swaps
Atomic swaps may become more accessible as blockchain infrastructure improves and decentralized applications develop better ways to coordinate transactions across networks.
Wallets and trading interfaces could hide much of the underlying complexity, allowing users to select the assets they want to exchange while software handles supported transaction conditions behind the scenes. Better monitoring, clearer refund procedures, and improved transaction-status reporting could also make cross-chain exchanges easier to understand.
At the infrastructure level, continued research into cryptographic techniques, interoperability, and transaction coordination may expand the range of possible cross-chain exchanges. However, broader adoption will depend on practical factors such as liquidity, cost, network compatibility, reliability, and security.
It is also important to distinguish atomic swaps from newer cross-chain systems that use messaging protocols, liquidity networks, or specialized execution environments. These approaches may provide different trade-offs in speed, convenience, and trust assumptions. Some applications may combine several mechanisms rather than rely on a single method.
For users and developers, the key question is not simply whether a protocol supports atomic swaps. It is whether the mechanism can deliver the required assets securely, at a reasonable cost, with clear execution and recovery procedures.
Ultimately, atomic swaps illustrate how blockchain networks can coordinate asset exchanges without necessarily depending on a conventional centralized exchange. Their role in cross-chain liquidity will depend on how effectively they address the practical challenges of interoperability, market depth, and user experience.
Interoperability Protocols and Messaging Networks
What Is Blockchain Interoperability?
Blockchain interoperability is the ability of separate blockchain networks to exchange information, coordinate actions, and support interactions across their different technical environments. It allows applications and users to work across multiple ecosystems instead of being limited to a single blockchain.
Each blockchain operates according to its own rules. Networks may use different consensus mechanisms, transaction formats, execution environments, security models, and methods for confirming transactions. As a result, one blockchain cannot automatically understand or verify everything that happens on another.
Interoperability protocols help bridge this communication gap. They provide systems through which information from one network can be transmitted to another and, where appropriate, used to trigger an action.
For example, a decentralized finance application on one blockchain might need to recognize that a user has deposited assets on another network. An interoperability protocol could relay information about the deposit so that the receiving application can respond according to its own rules.
This capability can support cross-chain liquidity, decentralized trading, lending, payments, and other blockchain applications. However, transmitting a message does not necessarily transfer an asset. Asset movement may also require a bridge, liquidity provider, token issuance mechanism, or another settlement process.
Understanding this distinction is important because interoperability is the communication layer that can connect different systems, while liquidity mechanisms determine how assets or economic value become available across those systems.
How Cross-Chain Messaging Works
Cross-chain messaging allows information generated on one blockchain to be delivered to an application or contract on another blockchain. The process typically involves several stages, although the precise architecture differs between protocols.
1. A source-chain event occurs.
A user initiates an action on the source blockchain. This might involve depositing a token, submitting a transaction, updating a contract, or requesting a cross-chain operation.
The source application generates a message containing the information needed for the intended action. Depending on the protocol, this message may include a destination network, recipient contract, transaction details, and additional verification data.
2. The message is observed and verified.
A protocol’s verification system determines whether the source-chain event is legitimate and sufficiently confirmed. Verification methods vary widely. Some systems use validators, some rely on external relayers and cryptographic proofs, and others employ specialized verification networks.
The receiving application must have a reliable way to determine that the message corresponds to a valid event on the source chain.
3. The message is transmitted.
Once the relevant verification requirements have been met, a relayer or messaging component delivers the message to the destination blockchain. The relayer’s exact responsibilities depend on the protocol. In some systems, relayers primarily transport messages, while separate mechanisms verify their authenticity.
4. The destination application processes the message.
The receiving contract checks the message against its own rules. If the required conditions are satisfied, it can execute the intended action. That action might update a record, authorize a transaction, release or mint tokens, or initiate another contract interaction.
5. The operation is confirmed and monitored.
The destination transaction must be included and sufficiently confirmed on the receiving network. Some protocols also provide message-status tracking or mechanisms for handling failed execution and retrying operations.
A successful message delivery does not guarantee that every subsequent action will succeed. Destination-chain congestion, insufficient funds for execution, contract errors, or other conditions may prevent the intended result.
This is why reliable cross-chain systems need more than message transmission. They also require robust verification, appropriate execution rules, and clear procedures for managing failures.
Interoperability Protocols and Cross-Chain Liquidity
Interoperability Protocols and Cross-Chain Liquidity
Interoperability protocols can support cross-chain liquidity by enabling applications on different blockchains to coordinate their operations.
Cross-chain liquidity protocols help coordinate transactions and asset transfers between supported blockchain networks. Depending on their design, they may use messaging systems, liquidity providers, bridges, or smart contracts to connect separate markets and improve access to decentralized financial services.
Imagine a decentralized lending application operating on one network and a user holding collateral on another. A cross-chain system might relay information about the user’s position or coordinate an action that allows the application to recognize assets held elsewhere. Depending on the design, additional infrastructure would still be needed to establish custody, collateral control, settlement, and enforceable risk limits.
Interoperability can also support cross-chain trading. A user might initiate a transaction through an application that communicates with several blockchain networks. Messaging infrastructure can coordinate parts of the operation, while liquidity providers or decentralized exchanges supply the assets required to complete the trade.
These systems can improve the experience of using multiple blockchains, but the economic result depends on the entire transaction path. Users still need sufficient liquidity, competitive exchange rates, reasonable fees, and a secure settlement mechanism.
Interoperability therefore acts as an enabling layer rather than a guarantee of abundant liquidity. It can help connect previously isolated markets, but it cannot create market demand or remove every technical and financial constraint.
Different Approaches to Cross-Chain Messaging
Cross-chain messaging systems can be designed in several ways. Each approach introduces different assumptions about verification, decentralization, performance, and security.
Validator-Based Messaging
Some protocols use a group of validators or network operators to observe events on one blockchain and attest that a message is valid. The receiving system relies on the protocol’s verification rules to determine whether the message should be accepted.
This approach can support flexible communication between networks, particularly when direct verification of the source blockchain is difficult for the destination chain.
However, the security of the system depends partly on the validator arrangement. Important questions include how validators are selected, how their responsibilities are distributed, what happens if they collude, and whether an attacker could compromise enough participants to approve a fraudulent message.
A larger validator group is not automatically more secure. The independence of its members, the verification rules, the incentives they face, and the consequences of failure all matter.
Light-Client and Proof-Based Messaging
Some interoperability designs use cryptographic proofs or light clients to verify information about another blockchain. A light client maintains or verifies selected information about the source chain rather than reproducing its entire state.
Depending on the architecture, the destination network may verify evidence that a particular event or state transition was accepted by the source blockchain. This can reduce reliance on an external committee’s assertion, although the system still depends on the correctness of its proof verification, assumptions about consensus, and implementation quality.
Proof-based verification can provide strong security properties, but it may introduce complexity, computational costs, or additional engineering requirements. Different blockchain architectures also make verification easier or harder to implement.
Relayer-Based Messaging
Relayers transport messages between blockchain networks. They may observe source-chain events, submit transactions to the destination chain, and help ensure that cross-chain instructions are delivered.
A relayer is not necessarily the entity that decides whether a message is trustworthy. In some systems, message authenticity is verified independently by contracts or cryptographic mechanisms. This separation can allow anyone to relay a valid message without giving that relayer unilateral control over the outcome.
However, the system’s design matters. If a protocol depends on a single relayer and has no alternative delivery mechanism, the relayer may become a point of failure for availability. Users and developers should understand whether messages can be submitted by multiple parties and whether delayed delivery can be recovered.
Optimistic Verification
Some systems use an optimistic model in which messages are accepted under defined assumptions unless a challenge or fraud-detection process identifies a problem. These designs may offer performance or cost advantages, but their security depends on the challenge mechanism, monitoring capabilities, and required waiting periods.
A system may need sufficient time for an invalid message to be challenged before the destination application acts on it. This can affect the speed and convenience of cross-chain transactions.
Optimistic verification should not be treated as inherently unsafe or inherently secure. Its suitability depends on the protocol’s incentives, proof mechanisms, operational requirements, and consequences of accepting an invalid message.
Messaging Protocols Versus Bridges
Messaging protocols and bridges are closely related, but they are not interchangeable concepts.
A bridge focuses on enabling assets or their representations to move between blockchain networks. Depending on its design, it may lock tokens, mint corresponding tokens, burn tokens, release previously deposited assets, or use destination-chain liquidity to fulfil transfers.
A messaging protocol focuses on transmitting and verifying information across networks. That information may concern an asset transfer, but it can also coordinate application actions that do not directly involve transferring tokens.
For example, a cross-chain lending application might use messaging to communicate a position update between networks, while a separate asset mechanism handles the movement or representation of collateral. In another design, a bridge may use a messaging system as part of its transfer process.
The distinction matters for security analysis. A bridge may face risks related to custody, liquidity reserves, token issuance, or asset release. A messaging protocol may face risks related to message verification, validator compromise, proof correctness, or unauthorized destination execution. A combined system can inherit risks from several components.
Before using a cross-chain application, users should understand which parts of the operation are handled by messaging infrastructure, which parts manage assets, and how the components depend on one another.
Security Risks in Cross-Chain Messaging
Cross-chain messaging expands the range of actions that applications can perform, but it also creates additional security considerations.
Invalid message acceptance: If a destination application accepts a fraudulent message, an attacker may be able to trigger unauthorized actions. Verification rules must ensure that messages originate from legitimate sources and satisfy the protocol’s requirements.
Validator or verification compromise: If a system relies on a group of validators or other verification participants, an attacker may target those participants or exploit weaknesses in their coordination.
Replay attacks: A message may be submitted more than once if the protocol does not properly track processed messages or enforce unique transaction identifiers. Secure designs generally need protections against unauthorized repeated execution.
Incorrect destination execution: A valid message can still trigger an unintended result if the receiving contract contains a vulnerability or processes the message incorrectly. Source-chain authenticity alone does not guarantee the safety of destination-chain code.
Delayed delivery: Network congestion, relayer outages, or verification delays can prevent messages from arriving when expected. Delays may affect time-sensitive trading, collateral management, or other financial operations.
Failure to complete a multi-step operation: A cross-chain transaction may involve several messages and actions. If one step succeeds while another fails, the application must have a well-designed method for handling the resulting state.
Excessive permissions: A receiving contract may grant a cross-chain message the authority to execute powerful actions. Applications should restrict what messages can do and verify their intended sender, destination, and parameters.
These risks show why security assessments must consider the complete system rather than focusing only on the messaging layer.
Evaluating an Interoperability Protocol
Users, developers, and liquidity providers should examine several factors before relying on a cross-chain interoperability system.
First, they should understand how messages are verified. The protocol should clearly explain its verification model and the assumptions required for the destination network to trust a message.
Second, they should examine decentralization and control. A system with a small number of privileged operators may have different risks from one that uses independently verifiable proofs or a broader verification network. The number of participants alone does not determine the quality of the security model.
Third, they should assess the protocol’s history and transparency. Public documentation, independent security reviews, disclosed incidents, and clear explanations of upgrades can help users understand how the system is maintained. An audit is useful evidence, but it does not guarantee that software is free from vulnerabilities.
Fourth, users should look at failure handling. They need to know what happens if a message is delayed, rejected, or executed unsuccessfully. Applications that provide clear transaction status and recovery instructions can reduce confusion during unexpected events.
Finally, users should consider the financial consequences of failure. A messaging error in a low-value application may have limited consequences, while a vulnerability affecting lending, token issuance, or large liquidity pools could cause substantial losses.
The Future of Interoperability and Messaging Networks
Interoperability infrastructure is likely to remain an important part of blockchain development as users and applications interact with more networks.
Future systems may offer more standardized message formats, improved verification methods, better monitoring, and simpler integration for developers. These improvements could make it easier for applications to coordinate actions across several chains without requiring users to understand every technical step.
Wallets and decentralized applications may also increasingly handle cross-chain operations through unified interfaces. Users could select an asset or action while the application identifies supported routes, estimates fees, checks execution requirements, and monitors the transaction. Such convenience will be valuable only if the underlying verification and asset-handling mechanisms remain reliable.
Another important development is the separation of communication from settlement. A messaging protocol can transmit instructions, while specialized systems manage liquidity, execution, or asset transfers. Modular designs can make infrastructure more flexible, but they may also introduce additional dependencies that need to be secured.
Ultimately, interoperability protocols and messaging networks help different blockchains work together without requiring them to become a single network. They can support cross-chain liquidity by coordinating information and actions, but their effectiveness depends on secure verification, reliable execution, available liquidity, and transparent risk management.
Wrapped Assets, Native Assets, and Liquidity Representations
Understanding Native Crypto Assets
Native crypto assets are digital assets that exist directly on their own blockchain networks. They are typically used to pay transaction fees, participate in network operations, transfer value, or interact with applications built on the same blockchain.
For example, Bitcoin is the native asset of the Bitcoin network, while Ether is the native asset of Ethereum. Other blockchain ecosystems have their own native assets that support their respective networks.
Native assets are important to cross-chain liquidity because each blockchain maintains its own transaction environment, account system, and rules for handling assets. A token held on one network does not automatically become available on another network simply because both networks support decentralized finance.
Suppose a user holds Ether on Ethereum but wants to use a decentralized application on another blockchain. The user may need to transfer value through a compatible bridge, exchange Ether for an asset available on the destination network, or use another supported cross-chain mechanism.
The method depends on the networks involved and the services available. Some systems move an asset’s economic value through a liquidity provider, while others create a token representation on the destination network.
Understanding where an asset originates, how it is represented, and which mechanism supports its value is essential when evaluating cross-chain transactions.
What Are Wrapped Assets?
Wrapped assets are tokens designed to represent another asset within a particular blockchain environment. They allow users to interact with applications that cannot directly use the original asset in its native form.
A common example is Wrapped Bitcoin, often called WBTC, which represents Bitcoin on Ethereum through a specific token and custody arrangement. It allows eligible holders to access certain Ethereum-based applications without using Bitcoin directly on the Ethereum network.
The wrapped token and the original asset are not the same blockchain object. Bitcoin continues to exist on the Bitcoin network, while the wrapped representation exists on another network according to that network’s token rules.
The relationship between the two assets depends on the mechanism that issues, backs, redeems, or otherwise supports the wrapped token. In a custodial model, an organization or group of entities may hold the underlying asset and issue corresponding tokens. Other systems use different arrangements, including smart contracts, collateral, or decentralized mechanisms.
Wrapped assets can expand the range of applications available to users, but they also introduce additional considerations. Users need to understand what backs the representation, who controls the underlying asset where applicable, how redemption works, and what happens if the system experiences a security or operational failure.
A wrapped token should not be assumed to be risk-free simply because it is designed to track the value of a familiar cryptocurrency.
How Wrapped Assets Support Cross-Chain Liquidity
Wrapped assets help connect blockchain ecosystems by making an asset representation available on a network that cannot directly process the original asset.
Imagine that a user owns Bitcoin but wants to participate in an Ethereum-based lending application. The user may be able to obtain a supported Bitcoin representation on Ethereum and then use that token within compatible decentralized finance protocols.
This can create additional utility for capital that might otherwise remain limited to its original network. Instead of selling the underlying asset outright, the holder may gain access to lending, trading, liquidity provision, or other financial services, depending on the token and application’s requirements.
Wrapped assets can also help decentralized exchanges create trading pairs between tokens that originate from different blockchain ecosystems. A wrapped representation can be exchanged against stablecoins or other tokens available within the same network.
However, the availability of a wrapped token does not guarantee deep liquidity. A token may exist on a blockchain but have few trading pairs, limited liquidity-provider participation, or little demand. Users may encounter high slippage or difficulty exiting a position.
The usefulness of a wrapped asset therefore depends on more than its technical availability. It also depends on market depth, redemption arrangements, security, acceptance by applications, and confidence in the system that supports its value.
How Wrapped Assets Are Created and Redeemed
The process for creating a wrapped asset varies by protocol, but many systems follow a general pattern.
1. The underlying asset is deposited or committed.
A user transfers an eligible asset to the mechanism responsible for supporting the wrapped representation. Depending on the design, the asset may be held by a custodian, locked in a contract, or managed through another arrangement.
2. The deposit is verified.
The system checks that the required transaction has occurred and satisfies the relevant conditions. Verification may involve authorized operators, blockchain proofs, validators, or other protocol-specific mechanisms.
3. A wrapped token is issued.
Once the required conditions are satisfied, the system creates or releases the corresponding token representation on the destination blockchain. The issued quantity follows the protocol’s rules and may depend on the amount deposited, fees, and eligibility requirements.
4. The token is used on the destination network.
The holder can use the wrapped asset in supported applications, subject to the token’s design and the rules of each application. The representation may be traded, deposited into a liquidity pool, or used as collateral if the relevant protocol accepts it.
5. Redemption reverses the process.
Where redemption is supported, a holder submits the wrapped token for the required redemption process. The token may be burned or otherwise removed from circulation, and the corresponding underlying asset is released according to the system’s rules.
These steps describe a general model rather than a universal process. Some cross-chain systems use liquidity pools to deliver destination assets instead of issuing a one-to-one wrapped representation. Others use specialized token standards or more complex verification mechanisms.
Before using a wrapped token, users should confirm that its issuance and redemption model is clearly documented and that the relevant redemption route is actually available to them.
Wrapped Assets Versus Bridged Native Assets
The terms wrapped asset and bridged asset are sometimes used interchangeably, but they can describe different aspects of a cross-chain transaction.
A wrapped asset is generally a token representation of another asset. A bridged asset is a broader term that may describe an asset transferred or represented through a cross-chain mechanism.
For example, a bridge may lock a token on the source network and issue a corresponding token on the destination network. That destination token may be described as a wrapped or bridged representation, depending on the protocol’s terminology.
Another bridge may burn tokens on the source chain and mint equivalent tokens on the destination chain. This approach can preserve a relationship between supplies across supported networks without necessarily using the same custody model as a conventional wrapped token.
A liquidity-based bridge may instead deliver an existing asset from a destination-chain liquidity pool. In that case, the user receives an asset already available on the destination network rather than necessarily receiving a newly minted representation of the source asset.
These differences matter because the security assumptions are not identical.
A token backed by assets held by a custodian introduces questions about custody, reserves, and redemption. A token issued through a smart-contract bridge raises questions about contract security, cross-chain verification, and control over minting and burning. A liquidity-based bridge requires sufficient reserves and a reliable mechanism for settling the transaction.
Users should examine the actual architecture instead of relying only on the label attached to a token.
Liquidity Fragmentation Across Asset Representations
When an asset has several representations across different networks, its liquidity can become fragmented.
For example, a cryptocurrency might have a native version on its original blockchain, a wrapped version on Ethereum, and another bridged version on a separate network. Although these tokens may be designed to represent related economic value, each version can have its own trading pairs, liquidity pools, holders, and market conditions.
This fragmentation can make trading less efficient. One version may have substantial liquidity, while another has thin markets and higher price impact. The tokens may also trade at slightly different prices if market participants have concerns about redemption, bridge security, or the availability of arbitrage.
Consider two tokens that are intended to maintain a one-to-one relationship with the same underlying asset. If users lose confidence in the mechanism supporting one representation, its market price could fall below the expected value of the underlying asset. The price difference may persist if redemption is difficult, costly, restricted, or unavailable.
Cross-chain liquidity infrastructure can help users access different markets, but it does not automatically combine every representation into one unified pool.
Developers and liquidity providers can reduce some of these inefficiencies by improving routing, supporting reliable redemption mechanisms, and building deeper markets. Nevertheless, the underlying differences between token representations remain important.
Depegging and Redemption Risks
A wrapped asset is often designed to track the value of an underlying cryptocurrency at a defined ratio. However, the expected relationship may weaken if the system encounters problems.
A depeg occurs when a token’s market price moves away from its intended reference value. For example, a wrapped token intended to represent one unit of an underlying asset may trade below that value because traders are concerned about whether the token can be redeemed.
Several factors can contribute to a depeg.
Custody concerns: If users doubt whether the underlying assets are safely held, they may become reluctant to purchase the wrapped representation.
Bridge vulnerabilities: An exploit affecting the mechanism that issues or supports a wrapped token may undermine confidence in its backing or redemption process.
Redemption delays: If holders cannot promptly exchange the representation for the underlying asset, market prices may diverge from the expected value.
Insufficient liquidity: A token with limited trading depth can experience large price movements when holders try to sell significant quantities.
Operational restrictions: Legal, technical, or administrative limitations may prevent some users from redeeming assets under certain circumstances.
Market stress: During periods of extreme volatility, liquidity providers may withdraw capital and arbitrage opportunities may become harder or more expensive to execute.
A token’s intended backing ratio does not guarantee that every holder can immediately redeem it at the expected value. Users should examine the actual redemption process, eligibility requirements, fees, and dependencies.
Evaluating Wrapped Tokens Before Using Them
Before holding a wrapped asset or depositing it into a decentralized finance application, users should consider several important questions.
What asset does the token represent? Confirm the underlying asset, the token’s purpose, and the blockchain on which the representation exists.
How is the token supported? Determine whether the system relies on a custodian, smart contracts, collateral, validators, or another mechanism.
Can the token be redeemed? Review whether holders can obtain the underlying asset and what conditions, fees, or restrictions apply.
Who controls issuance? Understand which parties or contracts can mint, burn, freeze, or otherwise affect the token’s supply.
Has the system undergone independent security reviews? Look for relevant audits, publicly documented incidents, and information about how vulnerabilities are handled. Audits can reduce uncertainty but cannot eliminate risk.
Is there sufficient liquidity? Check trading depth, available trading pairs, price differences, and the potential cost of exiting a position.
Does the receiving application accept this exact token? Tokens with similar names may have different contracts, issuers, or backing arrangements. Users should verify the exact network and token contract supported by the application.
What happens if the supporting system fails? Consider whether the token could become difficult to transfer, trade, or redeem if a custodian, bridge, validator network, or smart contract becomes unavailable.
These checks help users distinguish between a token’s intended purpose and the practical guarantees its design can actually provide.
The Future of Wrapped Assets and Liquidity Representations
Wrapped assets are likely to remain relevant while blockchain ecosystems use different transaction systems and applications require token representations that can operate within their own environments.
Improvements in interoperability may make it easier to verify asset movements, coordinate issuance and redemption, and monitor the supply of related tokens across networks. Better liquidity routing may also help users find more competitive trading paths between supported representations.
At the same time, developers are exploring approaches that reduce reliance on particular custodians or make cross-chain operations more transparent. These approaches can introduce their own technical and economic trade-offs, so users will still need to understand the underlying architecture.
Another potential development is the use of more standardized asset representations. Consistent token identification, clearer redemption rules, and better disclosure of backing arrangements could make it easier for applications and users to distinguish between different versions of an asset.
However, standardization alone will not eliminate risks. A token’s security will continue to depend on the mechanism that supports it, the quality of its implementation, the liquidity available in relevant markets, and the ability of holders to exercise their rights.
Ultimately, wrapped assets can extend the usefulness of cryptocurrencies across blockchain ecosystems, but every representation introduces specific assumptions. Understanding those assumptions is essential for managing risk and making informed cross-chain liquidity decisions.
Liquidity Aggregators and Routing Systems
What Are Liquidity Aggregators?
Liquidity aggregators are platforms or protocols that search across multiple liquidity sources to help users find suitable trading or transaction routes. Instead of relying on a single exchange, liquidity pool, or service provider, an aggregator can compare available options and identify a route that may offer a better overall outcome.
In decentralized finance, liquidity can be distributed across automated market makers, decentralized exchanges, lending protocols, and different blockchain networks. This fragmentation can make it difficult for users to identify the most efficient way to exchange assets or complete a cross-chain transaction.
Liquidity aggregators help address this challenge by collecting information about available markets, estimating transaction costs, and evaluating possible routes. Depending on their design, they may also divide a transaction among several liquidity sources to reduce price impact or improve execution.
For example, a user may want to exchange a token on one blockchain for a stablecoin on another. A cross-chain aggregator might evaluate several possible routes involving a token swap, a bridge, destination-chain liquidity, or an interoperability mechanism.
The aggregator can then present an estimated route based on factors such as expected output, network fees, slippage, transaction time, and supported services.
However, aggregation does not guarantee the best possible execution. Estimates can change, liquidity can disappear, and transactions may fail. The quality of the result depends on the aggregator’s supported networks, pricing data, routing logic, and underlying providers.
How Cross-Chain Routing Systems Work
Cross-chain routing systems determine how a transaction can move between different blockchain environments. Their purpose is to connect the necessary steps while considering cost, liquidity, execution requirements, and other constraints.
Although individual implementations differ, the process commonly involves several stages.
1. The user defines the transaction.
The user selects the asset they want to send, the amount, the destination blockchain, and the asset they want to receive. Some interfaces also allow users to specify a minimum acceptable output or other transaction preferences.
2. The aggregator identifies available routes.
The system searches the liquidity sources and cross-chain services it supports. These may include decentralized exchanges, automated market makers, bridges, liquidity networks, and messaging or settlement protocols.
A route may involve several operations. For example, the source token might first be exchanged for an intermediate asset, transferred to another network, and then exchanged for the destination token.
3. The system estimates the total cost.
The aggregator evaluates expected output alongside transaction fees, price impact, slippage, and other charges. Depending on the implementation, it may also estimate completion time and assess whether the required liquidity is available.
4. A route is selected.
The routing engine chooses a route according to its optimization criteria. Some aggregators prioritize the highest expected output, while others consider factors such as speed, reliability, supported assets, or user-defined limits.
The route with the lowest displayed fee is not necessarily the cheapest overall. A route with poor liquidity may produce a worse exchange rate, even if its explicit service fee is low.
5. The transaction is executed.
The user authorizes the required transactions, and the system begins processing the route. Depending on the design, different steps may execute on separate blockchains or through different service providers.
6. The transaction is monitored.
The system tracks progress where possible and reports whether the transaction has completed, failed, or remains pending. Multi-step transactions can encounter delays if one of the networks becomes congested or a service provider experiences an operational issue.
A reliable routing experience therefore requires more than selecting a path. It also requires accurate estimates, suitable transaction protections, and clear reporting when something goes wrong.
Why Liquidity Aggregation Matters
Liquidity aggregation can improve the efficiency of cross-chain transactions by making fragmented markets easier to access.
Access to Multiple Liquidity Sources
A user trading through a single exchange may only access the liquidity available within that platform. An aggregator can search across several supported sources, potentially identifying a better price or a route that would otherwise be difficult to discover.
This is particularly useful when liquidity is spread across multiple decentralized exchanges or blockchain networks.
However, the benefits depend on which sources the aggregator actually supports. A platform cannot compare markets it does not monitor or access.
Reduced Price Impact
Price impact occurs when a trade changes the market price because the available liquidity is insufficient for the order size.
An aggregator may reduce price impact by identifying deeper pools or distributing a transaction across several sources. For example, rather than executing an entire trade against one small pool, the routing system may use two or more pools if doing so produces a better estimated result.
Splitting a trade is not always beneficial. Additional transactions can increase network fees, and prices may change before every component executes.
Improved Capital Efficiency
Liquidity aggregation can help capital serve a wider range of trading needs. Instead of requiring every application to rely on one isolated pool, routing systems can direct transactions toward available liquidity across supported markets.
This can improve how efficiently users access existing capital. Nevertheless, aggregation does not physically combine every pool into one shared reserve. Each source continues to have its own balances, pricing mechanism, and operational constraints.
Better User Experience
Cross-chain transactions can involve several complex steps. Aggregators can hide much of this complexity behind a single interface, helping users select a destination asset without manually navigating every bridge and decentralized exchange.
A simplified interface is useful, but users should still understand the major transaction details, including the route, expected output, fees, security assumptions, and recovery options.
Single-Chain Aggregators Versus Cross-Chain Aggregators
Single-chain and cross-chain aggregators share the goal of improving transaction execution, but they operate across different environments.
A single-chain aggregator searches for routes within one blockchain. It may compare decentralized exchanges, automated market makers, and other liquidity sources that operate on the same network.
Because the transaction remains within one blockchain, the aggregator generally does not need to coordinate asset movement between separate networks. It must still account for network fees, contract interactions, price impact, and transaction failure.
A cross-chain aggregator must consider additional requirements. It may need to identify a bridge or transfer mechanism, evaluate liquidity on both the source and destination networks, coordinate multiple operations, and account for different confirmation and finality conditions.
For example, exchanging Token A for Token B on one blockchain may require only a swap. Exchanging Token A on one network for Token B on another may require a source-chain transaction, a cross-chain transfer or settlement process, and a destination-chain swap.
Each additional component introduces costs and possible failure points.
Cross-chain aggregators can therefore offer broader access to liquidity, but their routing decisions may be more complex than those of single-chain systems.
How Aggregators Compare Transaction Costs
An effective aggregator should consider the total economic cost of a transaction rather than focusing on a single fee.
Network fees: These are charges associated with processing transactions on the relevant blockchains. A cross-chain route may require fees on both the source and destination networks.
Trading fees: Decentralized exchanges and liquidity pools may charge fees for executing swaps. A route involving several swaps can accumulate multiple trading fees.
Price impact: Large trades relative to available liquidity can move the market price and reduce the amount received.
Slippage: The actual execution price may differ from the quoted price because market conditions change between the estimate and transaction execution.
Bridge or transfer fees: Some cross-chain services charge explicit fees for moving assets or delivering destination-chain liquidity.
Protocol and service fees: An aggregator or an underlying provider may charge additional fees for routing, execution, or specialized services.
Failed-transaction costs: Depending on the blockchain and the point of failure, users may lose transaction fees even if the intended operation does not complete.
Time-related costs: Delayed transactions can expose users to changing market prices or cause them to miss an opportunity. These effects may not appear as a separate line item but can still affect the final result.
Suppose two routes offer different quoted outputs. Route A may have lower explicit fees but use a shallow liquidity pool, producing a larger price impact. Route B may charge more in service fees but access deeper liquidity and deliver more of the desired asset.
In that situation, comparing only the displayed fee would be misleading. The more useful measure is the expected net amount received after accounting for all relevant costs.
Users should also check whether the displayed estimate includes destination-chain fees and whether additional charges may be deducted before the final asset arrives.
Transaction Splitting and Multi-Route Optimization
Some aggregators divide a trade across multiple liquidity sources to improve the expected execution price.
This approach is often called trade splitting or multi-route optimization. Rather than sending the entire order through one pool, the routing system evaluates different combinations of available sources and allocates portions of the trade among them.
Consider a user exchanging a large quantity of a token. One liquidity pool may offer an attractive rate for a small trade but produce substantial price impact when handling the full amount. Another pool may have a different fee structure or deeper liquidity.
An aggregator can estimate whether dividing the trade between these sources would improve the overall result.
The optimization process must balance several factors:
- The liquidity available in each pool.
- Trading fees and expected price impact.
- The number of transactions required.
- Network costs and execution complexity.
- The possibility that market conditions change.
- Whether all selected routes can execute successfully.
A larger number of routes does not automatically mean a better result. Splitting transactions across many sources can add complexity and costs, especially on networks with expensive transaction fees.
Cross-chain routing introduces further challenges because different portions of a transaction may depend on separate networks or transfer mechanisms. A route that looks attractive in a preliminary estimate may become less favorable if one component is delayed or its liquidity changes.
For this reason, route optimization must account for practical execution conditions rather than relying exclusively on theoretical prices.
Risks Associated With Cross-Chain Aggregators
Cross-chain aggregators can simplify transactions, but they do not eliminate the risks of the infrastructure they use.
Smart Contract Vulnerabilities
An aggregator may rely on smart contracts to manage approvals, route assets, or coordinate transaction steps. Vulnerabilities in these contracts can create opportunities for attackers to steal funds or manipulate transaction execution.
Users should investigate the security history of the aggregator and its underlying protocols. Independent audits and public documentation can help, although neither guarantees complete protection.
Dependence on Third-Party Providers
A routing system may rely on external bridges, liquidity providers, relayers, or other services. A problem with one provider can delay or prevent a transaction even if the aggregator itself continues to operate.
The aggregator’s security and reliability therefore depend partly on the components it selects.
Inaccurate or Outdated Estimates
Market conditions can change rapidly. Liquidity may be withdrawn, token prices may move, and network fees may increase after a route has been quoted.
If the system relies on outdated information or fails to account for execution changes, the final outcome may differ from the initial estimate.
Routing Manipulation and Malicious Transactions
Users may encounter malicious websites, fraudulent interfaces, or transactions that request unnecessary permissions. A legitimate-looking interface can still expose users to risks if its domain, contracts, or transaction details have been compromised.
Users should verify the application they are using and review transaction approvals before signing. They should be particularly cautious when an interface requests permissions that appear unrelated to the intended operation.
Partial Execution and Failed Routes
A cross-chain operation may involve multiple transactions. One step can succeed while a later step fails, leaving the user with an intermediate asset or a transaction that requires further action.
The exact outcome depends on the route’s architecture. Some systems provide recovery procedures, while others may require the user to claim funds, retry a transaction, or contact the service provider.
Users should understand how a route handles failure before authorizing a transaction involving significant funds.
Concentration of Routing Power
If many users rely on a small number of aggregators or underlying service providers, operational problems or security failures can affect a large volume of cross-chain activity.
Concentration can also create dependence on particular routing algorithms, interfaces, or infrastructure operators. A system’s convenience should therefore be assessed alongside its resilience and the availability of alternative routes.
How Users Can Evaluate a Cross-Chain Aggregator
Before selecting an aggregator, users should review several practical factors.
Supported networks and assets: Confirm that the aggregator supports the exact source token, destination token, and blockchain networks required for the transaction.
Route transparency: Look for information about the route, including the bridge or transfer mechanism, intermediate assets, liquidity sources, and major transaction steps.
Total expected cost: Compare the expected amount received rather than relying only on headline fees. Check whether destination-chain costs and service charges are included.
Slippage protection: Review the minimum output or other protections available if the market price changes before execution.
Security practices: Examine available audits, contract documentation, incident disclosures, and the process for reporting vulnerabilities.
Failure recovery: Determine what happens if a route is delayed, partially executed, or unsuccessful. Clear recovery instructions are especially important for multi-step transactions.
Liquidity quality: Consider whether the route relies on sufficiently deep markets and whether the displayed output is realistic for the intended transaction size.
Operational reliability: Review transaction tracking, status reporting, and the availability of support documentation. These features can be valuable when a cross-chain operation takes longer than expected.
Control and permissions: Check the permissions required by the application and whether approvals can be limited to the intended transaction. Avoid granting unnecessary access to wallet assets.
No single factor can establish that an aggregator is safe or suitable for every user. A balanced assessment should consider security, cost, transparency, and the consequences of a possible failure.
The Future of Cross-Chain Liquidity Aggregation
Cross-chain aggregators may become increasingly important as users interact with more blockchain networks and liquidity becomes distributed across a broader range of decentralized applications.
Future systems may improve route discovery, transaction simulation, fee estimation, and failure monitoring. Better simulations could help users understand the likely outcome of a transaction before approving it, while improved monitoring could make it easier to identify delayed or unsuccessful steps.
Routing systems may also become more sophisticated in how they evaluate security. Rather than choosing routes exclusively by price, an aggregator could consider additional factors such as provider reliability, verification mechanisms, transaction complexity, and the risks associated with particular assets.
Another potential development is a more unified user experience. Users may increasingly specify the asset they want to receive while the underlying system identifies a suitable route across supported networks. This could reduce the need to understand each individual bridge or decentralized exchange.
However, greater abstraction can also make it harder for users to see the assumptions behind a transaction. Transparent route information and clear risk disclosures will remain important as interfaces become simpler.
Cross-chain aggregation is not a guarantee of lower costs or safer transactions. Its value comes from comparing available options and coordinating access to fragmented markets. The best results will depend on reliable infrastructure, accurate information, competitive liquidity, and careful execution.
Ultimately, liquidity aggregators and routing systems can help connect blockchain markets and improve access to capital across ecosystems. Their effectiveness depends on how well they balance execution quality, transaction costs, security, and user protection.
Major Cross-Chain Liquidity Risks
Understanding the Risks of Cross-Chain Liquidity
Cross-chain liquidity creates opportunities for users to access digital assets, decentralized applications, and financial markets across different blockchain ecosystems. However, connecting separate networks also introduces risks that may not exist, or may be less significant, when using a single blockchain.
A cross-chain transaction can depend on several components, including smart contracts, bridge infrastructure, validators, messaging protocols, liquidity providers, and decentralized exchanges. If one component fails or becomes compromised, the effects can spread across the transaction route.
For example, a user may transfer an asset through a bridge, exchange it through a decentralized trading protocol, and deposit the resulting token into a lending application. Each step introduces its own requirements and potential failure points.
The transaction may depend on the bridge correctly verifying the transfer, the destination network processing the transaction, the exchange providing sufficient liquidity, and the lending protocol accepting the asset. A problem at any stage can affect the final outcome.
Cross-chain risk is therefore not limited to the possibility of a bridge being hacked. It also includes liquidity shortages, inaccurate pricing, token depegging, governance failures, operational interruptions, and weaknesses in the applications that use cross-chain infrastructure.
Understanding these risks is essential for users, developers, liquidity providers, and institutions that want to participate in decentralized finance across multiple networks.
1. Bridge Exploits and Unauthorized Asset Transfers
Bridge security is one of the most important concerns in cross-chain finance. Bridges often manage valuable assets or control the mechanisms that authorize token issuance and release. This can make them attractive targets for attackers.
Depending on the bridge architecture, an attacker who compromises the system may be able to withdraw locked assets, issue unauthorized tokens, manipulate transfer verification, or interfere with the settlement process.
For example, a bridge that locks tokens on one blockchain and issues corresponding tokens on another must reliably verify that each issuance is supported by a legitimate deposit or an equivalent authorized action. If an attacker can bypass that verification, the system may create representations that are not properly backed.
Different bridge designs face different risks. Custodial systems may depend on the security and integrity of the entities holding assets. Smart-contract bridges may depend on contract correctness and secure authorization mechanisms. Validator-based bridges may depend on the independence and security of their verification participants.
A bridge exploit can have consequences beyond the immediate loss. If the affected bridge supports a widely used wrapped token, decentralized exchange, or lending protocol, uncertainty about its backing may affect markets and applications that rely on the token.
Risk reduction: Users should examine the bridge’s security model, supported networks, audit history, known incidents, and procedures for responding to emergencies. Developers should limit privileged access, carefully verify cross-chain messages, and design systems that minimize the potential impact of a compromised component.
No audit or security claim guarantees that a bridge cannot be exploited. Users should avoid treating historical reliability as proof of future safety.
2. Smart Contract Vulnerabilities
Smart contracts automate the rules governing asset transfers, liquidity pools, token issuance, and cross-chain transactions. Their ability to execute without conventional intermediaries is valuable, but software errors can create serious vulnerabilities.
A smart contract may contain incorrect authorization rules, flawed accounting, unsafe external calls, or logic that behaves unexpectedly under unusual conditions. An attacker may exploit these weaknesses to steal assets, manipulate balances, or disrupt a protocol.
Cross-chain applications can be particularly complex because their contracts must account for events occurring on separate networks. Developers must consider how messages are verified, how repeated messages are handled, and what happens when an operation succeeds on one chain but fails on another.
A contract may also depend on another protocol’s assumptions. For example, a lending application might accept a bridged token as collateral without adequately accounting for the possibility that the bridge supporting that token could fail.
In such a case, the lending protocol’s contracts might operate exactly as programmed while the economic value of the collateral deteriorates sharply.
Risk reduction: Users should consider independent audits, publicly documented security practices, upgrade controls, and the protocol’s response to previous incidents. Developers should test unusual transaction sequences, establish appropriate permission limits, and assess the risks of external dependencies.
Smart contract audits are valuable, but they cannot guarantee that every vulnerability has been identified.
3. Liquidity Shortages and Withdrawal Pressure
Cross-chain liquidity depends on the availability of assets on the networks where users want to trade or receive them. If a destination network has insufficient liquidity, transactions can become expensive, experience significant slippage, or fail to execute.
Liquidity shortages can develop for several reasons. A market may have relatively few participants, liquidity providers may withdraw their funds, a popular trading route may experience heavy demand, or market volatility may cause providers to reduce their exposure.
Liquidity-based bridges are particularly dependent on the availability of suitable assets in their destination pools. If many users attempt to withdraw the same asset at once, a pool may not have enough reserves to fulfil every request immediately.
For decentralized exchanges, limited pool depth can also cause a large trade to move the market price significantly. A user may receive fewer tokens than expected even when the transaction completes successfully.
Liquidity shortages can become more serious during periods of market stress. Users may simultaneously seek to exit risky positions, while liquidity providers become less willing to supply capital.
This can create a cycle in which reduced liquidity leads to greater price impact, worsening prices discourage participation, and available liquidity declines further.
Risk reduction: Users should check available liquidity, estimated output, slippage, and withdrawal conditions before making a transaction. Liquidity providers should understand the risks of concentrated positions and consider how they would respond to sudden changes in market demand.
High reported trading volume does not necessarily guarantee sufficient liquidity for a large transaction. The depth of the market at the intended trade size is especially important.
4. Depegging and Loss of Asset Backing
Some cross-chain systems use wrapped or bridged tokens that represent assets held or managed elsewhere. These tokens are generally expected to maintain a defined relationship with the underlying asset, but that relationship can weaken.
A depeg occurs when a token’s market price moves away from its intended reference value. For example, a token designed to represent one unit of an underlying cryptocurrency may trade at a discount if users become concerned about redemption or backing.
Several events can contribute to depegging:
- A bridge exploit raises doubts about whether the token is fully supported.
- A custodian becomes unable to release the underlying assets.
- Redemption is delayed, restricted, or temporarily unavailable.
- Market participants sell the token faster than available liquidity can absorb.
- A technical failure prevents transfers between networks.
- Uncertainty about the protocol creates a loss of confidence.
A token can also lose liquidity without completely losing its backing. If holders cannot easily redeem or trade it, the market price may diverge from the expected value even when the underlying assets still exist.
This distinction is important because the market value of a token depends not only on its intended design but also on the practical ability of holders to transfer, sell, or redeem it.
Risk reduction: Users should investigate the token’s backing mechanism, redemption arrangements, liquidity, and dependencies before treating it as equivalent to the original asset. Applications that accept bridged collateral should consider the possibility that the token’s market value may decline sharply.
5. Validator and Verification Risks
Many cross-chain systems rely on validators, operators, relayers, or other components to observe events and help verify messages between networks. These participants may perform different roles, and the security assumptions vary by protocol.
If a system relies on a limited group of entities to approve cross-chain actions, a sufficiently serious compromise may allow unauthorized messages to be accepted. Even without malicious behavior, operational failures or coordination problems can interrupt service.
The relevant risks depend on the architecture. A system that verifies cryptographic proofs on the destination chain may rely less on an external committee’s judgment for message authenticity. A validator-based system may instead depend on a defined threshold of independent participants following the protocol correctly.
The number of validators alone does not establish security. Their independence, permissions, incentive structure, monitoring, and ability to withstand coordinated attacks all matter.
Users should also distinguish between message delivery and message verification. A relayer may simply transport a message, while a separate mechanism determines whether the message is valid. In other designs, the responsibilities may be more closely connected.
Risk reduction: Users and developers should review the protocol’s verification model, validator responsibilities, emergency procedures, and safeguards against unauthorized actions. Systems should clearly document which entities can approve, delay, or prevent cross-chain operations.
6. Liquidity Provider and Impermanent Loss Risks
Liquidity providers supply assets to trading pools or other liquidity mechanisms in exchange for fees, incentives, or other potential returns. Their capital helps users execute transactions, but providing liquidity introduces financial risks.
One important risk is impermanent loss, which can occur when the relative prices of assets in a liquidity pool change. Depending on the pool’s design, the value of a provider’s position may be lower than the value of simply holding the same assets outside the pool.
Impermanent loss is not the only concern. Liquidity providers may also face smart contract vulnerabilities, bridge failures, sudden withdrawals, reduced trading activity, and changes in incentive programs.
Cross-chain liquidity providers may have additional exposure to the infrastructure used to move assets between networks. If a pool depends on a bridged token and the token loses confidence or becomes difficult to redeem, the provider’s position may suffer even if the pool’s own contracts continue operating.
Liquidity provision can also involve asymmetric exposure to market movements. Fees earned from trading may not fully compensate for price changes, losses, or security incidents.
Risk reduction: Providers should understand the pool’s pricing model, fee structure, asset composition, and dependencies. They should estimate potential losses under different market conditions rather than evaluating a position solely by its advertised annual percentage yield.
High yields can reflect additional risks or temporary incentives. They should not be interpreted as guaranteed returns.
7. Slippage, Price Impact, and Routing Errors
Cross-chain transactions often involve multiple steps, including token swaps, asset transfers, and destination-chain exchanges. Each step can affect the final amount received.
Slippage refers to the difference between an expected execution price and the actual execution price. Price impact refers to the effect a trade has on the market price because of the size of the order relative to available liquidity.
These effects can become more significant when transactions pass through several markets or use intermediate assets. A route that appears efficient at the beginning may become less attractive if prices move before every step completes.
Routing errors can also occur when an aggregator relies on incomplete market information, a provider becomes unavailable, or the selected route cannot execute under the current conditions.
A transaction may fail because it does not satisfy a minimum-output requirement, but the user may still pay network fees for the failed attempt. In more complicated systems, some stages may complete while others remain pending.
Risk reduction: Users should review the estimated output, minimum acceptable amount, transaction deadline where applicable, and the major components of the route. They should also understand whether a failed transaction can be retried and whether the assets remain accessible.
A lower advertised fee is not enough to establish that a route offers better value. The total expected outcome matters more.
8. Network Congestion and Transaction Delays
Cross-chain transactions depend on the operation of the participating blockchain networks. Congestion, higher transaction fees, delayed confirmations, and temporary service interruptions can affect the timing and cost of transfers.
A transaction may be submitted successfully but remain pending because the network is busy. A destination-chain action may also be delayed while the source transaction reaches the required confirmation threshold or the cross-chain message is processed.
Different blockchains have different definitions of transaction finality. Some provide relatively rapid confirmation, while others require additional time before a transaction is considered sufficiently settled for a particular application.
These differences can affect trading opportunities, collateral management, and other time-sensitive operations.
For example, a user who expects to move an asset quickly between networks may find that the transfer takes longer than anticipated. During that period, the asset’s market price could change, or the user may be unable to use the funds for another purpose.
Risk reduction: Users should review estimated completion times, network fees, confirmation requirements, and the status-reporting capabilities of the service they are using. They should avoid assuming that every cross-chain transaction will complete within a fixed period.
9. Governance and Administrative Control
Some cross-chain protocols use governance systems to manage upgrades, change parameters, approve new networks, or respond to security incidents. Others rely on administrative keys or designated operators for particular functions.
These controls may be necessary to maintain and protect a protocol, but they can introduce additional trust assumptions.
If a small group can change critical settings, modify contract permissions, or pause important operations, users may be exposed to risks associated with those powers. Governance can also become contentious if token holders, operators, and other stakeholders disagree about a proposed change.
Poorly managed upgrades can introduce vulnerabilities or interrupt service. Conversely, the absence of a workable emergency response mechanism can make it difficult to address a serious exploit.
Users should therefore understand not only how a protocol operates under normal conditions but also who has authority to change its behavior.
Risk reduction: Review the protocol’s governance structure, upgrade process, administrative permissions, and public documentation. Look for clear explanations of how critical decisions are made and how users are informed about major changes.
Decentralization is not a simple yes-or-no property. A system may distribute some responsibilities widely while retaining concentrated control over other important functions.
10. Regulatory, Compliance, and Operational Risks
Cross-chain liquidity also operates within a broader legal and operational environment. Requirements may vary according to the jurisdiction, type of service, assets involved, and role of the participants.
Certain service providers may be subject to rules concerning customer verification, sanctions screening, custody, reporting, or the movement of funds. Regulatory changes can affect which services are available to users and how providers operate.
Operational issues can also affect access to assets. A custodial provider may experience an outage, a platform may restrict a particular transaction, or a service may change its supported networks.
These risks differ from smart contract vulnerabilities but can still affect a user’s ability to transfer, trade, or redeem assets.
Risk reduction: Users should review the applicable terms and requirements of the services they use. Institutions and businesses should obtain appropriate legal and compliance advice for their circumstances and avoid assuming that decentralized technology removes all regulatory obligations.
11. Composability and Systemic Risk
Composability allows decentralized applications to interact with one another. A single asset may be used as collateral in a lending protocol, traded through a decentralized exchange, and incorporated into another financial strategy.
This interconnectedness can make capital more useful, but it can also transmit problems across several protocols.
For example, a cross-chain token may be used as collateral in multiple applications. If the mechanism supporting that token becomes compromised, uncertainty about its value may affect lending markets, liquidity pools, and leveraged positions.
Forced liquidations or large withdrawals can then increase market pressure. If several protocols rely on the same bridge, token representation, or verification system, one failure may have consequences across the broader ecosystem.
This does not mean that every cross-chain incident will produce widespread losses. The extent of the impact depends on exposure levels, protocol design, available safeguards, and how quickly the problem is contained.
Risk reduction: Developers and institutional users should assess dependencies across the entire transaction path. Protocols can reduce potential damage by limiting exposure, using conservative collateral parameters, monitoring critical dependencies, and preparing clear incident-response procedures.
Practical Steps for Reducing Cross-Chain Risk
Although cross-chain systems cannot eliminate every source of risk, users can take practical steps to make more informed decisions.
- Verify the network and token. Confirm the exact blockchain, token contract, destination address, and supported asset before authorizing a transaction.
- Research the service provider. Review documentation, security assessments, known incidents, and the protocol’s explanation of its security model.
- Check liquidity and transaction costs. Examine the expected output, price impact, slippage, bridge fees, and destination-chain costs.
- Understand the transfer mechanism. Determine whether the service uses a custodian, a smart-contract bridge, a validator network, a liquidity pool, or another arrangement.
- Use appropriate transaction limits. Where available, set reasonable minimum-output limits and avoid authorizing transactions whose terms you do not understand.
- Review wallet permissions. Check the contracts and permissions involved, and avoid granting broader access than the application needs.
- Start with a small test transaction when appropriate. A small transfer can help confirm that the network, address, and destination process work as expected. However, a successful test does not guarantee that a larger transaction will be safe.
- Keep records of transaction identifiers. Transaction hashes and status information can help users investigate delays or failures.
- Avoid concentrating unnecessary exposure. Consider the consequences of relying heavily on one bridge, token representation, liquidity provider, or protocol.
- Prepare for failure. Understand the available refund, retry, redemption, or support procedures before moving substantial capital.
These steps can reduce avoidable mistakes, but they cannot guarantee protection against every exploit, market event, or operational failure.
Why Risk Management Matters for the Future of Cross-Chain Liquidity
The long-term development of cross-chain finance depends partly on the industry’s ability to make connected blockchain systems more reliable.
Improvements in smart contract security, message verification, monitoring, and transaction recovery could reduce certain technical risks. More transparent reporting about reserves, dependencies, and governance could also help users evaluate the systems they rely on.
At the same time, cross-chain infrastructure is likely to remain diverse. Different protocols will continue to make different trade-offs between cost, speed, decentralization, flexibility, and security. No single design can be assumed to offer the best outcome in every situation.
Users and developers should therefore avoid treating interoperability as an automatic guarantee of safety. Connecting two networks creates new opportunities, but it also creates new dependencies that must be understood and managed.
Ultimately, sustainable cross-chain liquidity requires more than the ability to move assets between blockchains. It requires dependable infrastructure, transparent risk assumptions, realistic liquidity conditions, and clear procedures for handling failures.
Security, Decentralization, and Trust Assumptions
Why Trust Matters in Cross-Chain Liquidity
Cross-chain liquidity allows users to transfer, exchange, and use digital assets across separate blockchain networks. However, connecting these networks requires mechanisms that can verify transactions, coordinate operations, and ensure that assets are handled according to the intended rules.
A blockchain can independently verify transactions within its own environment, but it does not automatically know whether an event on another blockchain is genuine. Cross-chain infrastructure must therefore establish a reliable way to communicate information and determine which actions should be accepted.
This introduces an important question: What must a user trust when moving assets between blockchains?
The answer depends on the protocol’s architecture. Some systems rely on custodians, some use groups of validators, and others employ cryptographic proofs or combinations of different verification mechanisms. Each approach creates its own assumptions about security, control, and reliability.
Understanding these assumptions is essential because a cross-chain transaction may involve several independent components. Even if the source and destination blockchains are secure, a weakness in the bridge, messaging protocol, token issuer, or application could still put funds at risk.
Security therefore depends on the entire transaction path, not simply on the reputation of the blockchain being used.
What Are Trust Assumptions?
Trust assumptions are the conditions a system relies on to operate securely. They identify which participants, mechanisms, software components, or external services must behave correctly for the intended outcome to occur.
For example, a cross-chain bridge may rely on a group of validators to confirm that assets have been deposited on the source blockchain. The destination network may then accept the validators’ confirmation and issue a corresponding token.
In this design, users need to understand how the validators are selected, how their approvals are verified, and what could happen if enough of them become compromised or collude.
Another bridge may use cryptographic proofs that allow the destination chain to verify certain information about the source chain. This can reduce dependence on an external committee’s assertion, but the system still relies on correct proof generation, verification logic, and implementation.
A custodial service introduces a different set of assumptions. Users may depend on an organization to hold assets securely, maintain accurate records, and honour withdrawals under the service’s terms.
These examples demonstrate that different cross-chain systems distribute trust in different ways. The important question is not whether a protocol requires trust in an absolute sense, but where that trust is placed, how it is limited, and what happens if an assumption fails.
Centralized, Federated, and Decentralized Security Models
Cross-chain infrastructure can use different approaches to control and verification.
Centralized Models
A centralized bridge or service may rely on a single organization or a small group of authorized operators to control important functions.
This structure can make operations easier to coordinate. A provider may be able to process transactions efficiently, manage customer support, and respond quickly to certain operational problems.
However, users may need to trust the provider’s security practices, financial controls, operational reliability, and ability to fulfil its obligations.
If the provider controls the underlying assets or the keys required to release them, users may also be exposed to custody risks. Operational failures, compromised credentials, insolvency, or administrative decisions can affect access to funds.
Centralization is not automatically equivalent to insecurity, but it creates particular dependencies that users should understand.
Federated Models
A federated system distributes selected responsibilities among several independent or semi-independent participants. These participants may jointly approve transactions, verify events, or manage other critical functions.
Federation can reduce dependence on a single operator. A properly designed threshold mechanism may require several participants to approve an action before it can proceed.
However, the security benefit depends on how independent the participants actually are. If they share infrastructure, ownership, administrative control, or other important dependencies, the apparent distribution of responsibility may provide less protection than expected.
Users should examine the approval threshold, participant selection, incentives, and safeguards against collusion.
Decentralized Models
Decentralized systems aim to distribute important responsibilities across a broader network of participants or rely on verification rules that do not give one organization unilateral control.
Some designs use on-chain verification, cryptographic proofs, distributed validator networks, or combinations of these mechanisms.
Decentralization can reduce certain forms of centralized control, but it does not eliminate every risk. A decentralized protocol may still contain vulnerable contracts, depend on concentrated infrastructure, or rely on external systems for asset prices and transaction execution.
A protocol’s decentralization should therefore be evaluated by examining its actual control structure, verification mechanisms, upgrade permissions, and dependencies rather than relying solely on its marketing description.
Cryptographic Proofs and Independent Verification
Cryptographic proofs can help blockchain systems verify information without relying entirely on another party’s assertion.
In some cross-chain designs, a destination network can verify evidence that a transaction, event, or state transition occurred on the source blockchain. This may reduce the need to trust a separate group of operators to report what happened.
For example, a proof-based bridge might require evidence that a deposit satisfies the source network’s rules before the destination system releases assets or creates a corresponding token.
The value of this approach depends on the proof system and its implementation. The destination contract must verify the proof correctly, and the system must account for the source blockchain’s consensus and finality characteristics.
Cryptographic verification can also introduce technical complexity. Proof generation may require specialized infrastructure, while verification may have computational or implementation costs. Different blockchain environments may support different verification methods.
It is also important to distinguish proof validity from application safety. A proof may correctly establish that an event occurred, but the destination application could still contain a vulnerability or make an unsafe decision based on that event.
Proof-based verification can strengthen cross-chain security, but it must be combined with sound application logic and careful system design.
Validator Networks and Threshold Security
Many cross-chain protocols use validator networks or other groups of participants to help verify messages and coordinate transactions.
These systems may require a threshold of participants to sign or approve an operation. The threshold is intended to prevent a single compromised participant from authorizing an invalid action.
However, the security of a threshold mechanism depends on more than the number of participants. It also depends on the minimum number required to approve an operation, the independence of the participants, their key-management practices, and the protocol’s response to suspicious activity.
If the required threshold can be compromised, an attacker may be able to authorize fraudulent messages or transfers. If too many participants become unavailable, the system may be unable to process legitimate operations.
This creates a balance between security and availability.
A system with strict approval requirements may resist certain attacks but become less responsive when participants are offline. A system that prioritizes rapid operation may need additional safeguards to prevent unauthorized approvals.
Users should also consider how validator membership changes over time, whether participants are publicly identified, and how the protocol handles a suspected compromise.
A well-designed validator network should make its security assumptions understandable and provide clear information about the authority its participants possess.
Smart Contract Security and Upgrade Controls
Smart contracts often determine how cross-chain messages are accepted, how assets are issued or released, and which transactions are permitted.
Because these contracts can control valuable assets, their security is a fundamental part of the trust model.
Developers must consider authorization checks, transaction accounting, message verification, replay protection, and the handling of unusual execution conditions. Cross-chain applications also need to manage situations in which one operation completes but a related operation on another network fails.
Upgrade controls introduce another important consideration.
Some protocols allow administrators or governance participants to modify contract logic. This can help developers correct vulnerabilities or adapt to changing network conditions. However, upgrade authority may also create risks if the relevant keys are compromised or if a harmful change is approved.
Users should understand whether a protocol’s contracts are upgradeable, who can authorize upgrades, whether changes require a delay, and what safeguards exist for emergency actions.
A protocol that cannot be upgraded may face difficulties responding to certain vulnerabilities. A protocol with unrestricted upgrade powers may expose users to excessive administrative control.
The goal is to balance adaptability with accountability and appropriate limits on authority.
The Importance of Economic Security
Cross-chain security is not purely a technical problem. Economic incentives can influence whether participants act honestly, provide sufficient liquidity, and maintain reliable infrastructure.
Some systems require validators or service providers to stake assets, receive fees, or face penalties for certain forms of misconduct. These mechanisms can encourage honest behaviour, but their effectiveness depends on how they are designed.
For example, a penalty may discourage an attack only if it can be reliably enforced and is sufficiently meaningful relative to the potential gain. If the economic value that could be stolen exceeds the effective cost of compromising the system, the incentive structure may be inadequate.
Liquidity providers also respond to economic conditions. They may withdraw capital when expected returns no longer compensate for market risk, smart contract exposure, or uncertainty about a bridge.
This can reduce available liquidity even if the protocol continues operating correctly.
Economic security therefore includes the incentives facing validators, liquidity providers, governance participants, and other operators. It also includes the potential losses that could arise from a successful attack or a sudden change in market conditions.
A protocol’s security model should account for both technical vulnerabilities and the economic motivations of the participants involved.
Speed, Security, and Decentralization: Finding the Balance
Cross-chain systems often need to balance several objectives.
Speed matters because users generally want transactions to complete quickly. Shorter processing times can improve trading experiences and make decentralized applications more convenient.
Security matters because users need confidence that transfers, messages, and contract operations will be processed correctly.
Decentralization matters because distributing control can reduce dependence on a single organization or a small number of privileged participants.
These objectives can reinforce one another in some designs, but they can also involve trade-offs.
A protocol may rely on a fast external verification network to reduce transaction delays, but users must understand the security assumptions introduced by that network. Another system may require more extensive verification before completing a transfer, potentially increasing the time required.
A design that distributes responsibilities widely may improve resistance to certain forms of control, but coordination and maintenance can become more complicated. Conversely, a tightly controlled system may respond quickly to emergencies but require users to place greater trust in its administrators.
There is no single configuration that is best for every use case. A low-value transfer, a high-value institutional transaction, and a time-sensitive decentralized finance operation may have different requirements.
Users should evaluate the trade-offs in the context of the assets involved and the consequences of a possible failure.
How to Evaluate a Cross-Chain Protocol’s Trust Model
Before using a cross-chain protocol, users and developers should examine the following questions.
1. Who controls the assets?
Determine whether funds are held by a custodian, locked in smart contracts, distributed among liquidity providers, or managed through another arrangement.
2. How are cross-chain messages verified?
Understand whether the system relies on validators, cryptographic proofs, external attestations, or a combination of mechanisms.
3. Who can authorize important actions?
Review which participants can issue tokens, release assets, pause transactions, change permissions, or modify contract logic.
4. What happens if a critical component fails?
Look for documented procedures covering validator outages, bridge exploits, delayed messages, and unsuccessful transactions.
5. How independent are the security participants?
Consider whether validators, operators, or infrastructure providers share ownership, technical dependencies, or administrative control.
6. How are upgrades managed?
Review administrative permissions, governance arrangements, upgrade delays, and emergency procedures.
7. What security reviews are available?
Look for independent audits, public documentation, incident reports, and information about how vulnerabilities are addressed.
8. What are the consequences of a successful attack?
Consider the value exposed to the protocol, whether losses could affect other applications, and how much capital depends on the same infrastructure.
9. Can users withdraw or recover their assets?
Understand the conditions for withdrawals, redemption, refunds, and other recovery processes. Do not assume that every protocol offers a simple recovery route after a major incident.
10. Are the trust assumptions clearly disclosed?
A protocol should explain its important dependencies in language that users and developers can understand. If critical security arrangements are unclear, that uncertainty should be treated as a risk.
These questions help users look beyond transaction speed and advertised fees when choosing cross-chain infrastructure.
Building More Trustworthy Cross-Chain Liquidity
The long-term success of cross-chain liquidity will depend on systems that make their security assumptions clearer and limit the potential consequences of failure.
Several improvements can contribute to this goal.
First, protocols can strengthen message verification and asset accounting so that destination applications only act on valid cross-chain events.
Second, developers can reduce unnecessary privileges and limit the amount of capital exposed to a single contract or verification mechanism.
Third, monitoring and incident-response systems can help operators identify suspicious activity and respond before a problem spreads further. Such mechanisms must be designed carefully because emergency controls can also introduce administrative risks.
Fourth, protocols can improve transparency by documenting their architecture, dependencies, governance arrangements, and known limitations.
Finally, developers and users can assess security across the complete transaction path. Evaluating a bridge alone may be insufficient if the transaction also relies on a wrapped token, a decentralized exchange, and a lending protocol.
These improvements cannot eliminate every technical, economic, or operational risk. They can, however, make it easier to identify weaknesses and make informed decisions.
Ultimately, trustworthy cross-chain liquidity requires more than the ability to transfer assets between networks. It requires transparent trust assumptions, effective verification, carefully limited control, and realistic expectations about what each system can guarantee.
Real-World Examples Across Blockchain Ecosystems
Cross-chain liquidity is easier to understand when examined through real-world blockchain ecosystems. Different networks have developed their own approaches to decentralized finance, stablecoin transfers, token trading, and blockchain interoperability. These ecosystems often have different transaction costs, confirmation times, applications, and user communities, creating a need for mechanisms that allow capital to move between them.
Cross-chain liquidity does not depend on a single technology. It can involve blockchain bridges, liquidity pools, cross-chain messaging protocols, decentralized exchanges, wrapped assets, and liquidity aggregation systems. Each mechanism addresses a different part of the challenge of moving value between networks.
Understanding how these systems work in practice helps users, developers, and liquidity providers evaluate the opportunities and risks associated with interconnected blockchain finance.
12.1 Ethereum and Layer-2 Networks
Ethereum has a large decentralized finance ecosystem that includes lending platforms, decentralized exchanges, stablecoins, and liquid staking applications. However, activity on the Ethereum mainnet can become expensive when network demand increases.
Layer-2 networks address some of these limitations by processing transactions through separate execution environments while relying on Ethereum for important aspects of security or settlement, depending on the design of each network.
Examples include Arbitrum, Optimism, and Base. These networks support their own decentralized applications, liquidity pools, and trading communities. Although they are connected to Ethereum in different ways, liquidity is not automatically shared between them.
For example, a user may hold a stablecoin on Ethereum but want to use it in a decentralized exchange on Arbitrum. The user needs a supported method to move the asset or obtain an equivalent usable token on the destination network.
Depending on the selected route, the transaction may involve a canonical bridge, a third-party bridge, a liquidity-based transfer provider, or a cross-chain application. The route can differ in cost, speed, security assumptions, and available liquidity.
This creates several practical considerations:
- Transaction costs: The user may need to pay fees on the source network, the destination network, or both.
- Liquidity availability: The destination application must support the asset and have sufficient liquidity for the intended transaction.
- Transfer time: Some routes complete quickly, while others require additional confirmations or settlement periods.
- Security assumptions: The user should understand how the selected bridge or transfer mechanism verifies and processes transactions.
- Token compatibility: Tokens with similar names or symbols are not necessarily the same asset or supported by the same applications.
The Ethereum and Layer-2 ecosystem demonstrates an important principle: scaling transaction capacity does not automatically eliminate liquidity fragmentation. Cross-chain infrastructure helps users access applications across networks, but each route still has operational and security considerations.
12.2 Ethereum and Other Layer-1 Blockchains
Cross-chain liquidity also connects Ethereum with independent Layer-1 blockchains. Unlike Layer-2 networks that are designed to interact with an underlying settlement layer, independent Layer-1 blockchains may use different consensus mechanisms, virtual machines, validator structures, and transaction models.
For example, Ethereum and Solana have distinct technical architectures and application ecosystems. A token held on one network cannot generally be transferred directly to the other as if both chains shared a single ledger.
A user seeking to move value between these ecosystems may rely on a bridge, a cross-chain liquidity provider, a supported exchange service, or another interoperability solution.
Consider a user who holds an asset on Ethereum and wants to access a decentralized application on Solana. The user must determine whether the application accepts the asset, whether a supported transfer route exists, and whether the destination token represents the asset the user intends to hold.
The process may involve transferring an asset across networks or exchanging it for a different token available on the destination chain. These are not always equivalent actions. A cross-chain transfer aims to move value between ecosystems, while a cross-chain swap may also change the asset being held.
Several factors influence whether such a transaction is practical:
- The amount of liquidity available for the asset on both networks.
- The number of intermediaries or protocols involved in the route.
- The reliability of the bridge or interoperability infrastructure.
- The total cost of transferring and exchanging the asset.
- The availability of reliable token redemption or exit routes.
- The compatibility of the destination token with the user’s intended application.
This example highlights the importance of evaluating the complete transaction route rather than focusing only on the advertised transfer fee or estimated completion time.
12.3 Stablecoins as a Major Source of Cross-Chain Liquidity
Stablecoins are among the most important assets in cross-chain finance because they are commonly used for trading, payments, lending, collateral, and transferring value between applications.
However, stablecoin liquidity can be distributed across multiple networks. A stablecoin available on Ethereum may have different liquidity conditions from a version available on a Layer-2 network or an independent blockchain.
Even when two tokens share the same brand and target the same currency value, their technical representations and transfer arrangements may differ.
Some stablecoin issuers support native issuance or official transfer mechanisms across multiple networks. Other cross-chain arrangements depend on third-party bridges or wrapped representations. The distinction matters because the token’s redemption process, security model, and relationship to the underlying issuer may differ.
For example, a trader may want to move dollar-denominated stablecoin value from one blockchain to another to access a lending market with more attractive borrowing conditions. Before transferring, the trader needs to consider whether the destination market has enough liquidity, whether the stablecoin is accepted as collateral, and whether the cost of moving funds outweighs the potential benefit.
Stablecoin transfers may support several activities:
- Moving trading capital between decentralized exchanges.
- Supplying assets to lending and borrowing protocols.
- Funding decentralized applications on a different network.
- Providing liquidity to pools where demand is stronger.
- Transferring value between payment applications.
- Managing collateral across supported blockchain environments.
Nevertheless, stablecoins are not risk-free. Users must consider issuer risk, redemption terms, contract security, bridge design, liquidity conditions, and the possibility that a token’s market price could temporarily diverge from its intended value.
Cross-chain stablecoin liquidity is most useful when users can access a supported asset through a reliable route with transparent costs and manageable risks.
12.4 Decentralized Exchanges and Cross-Chain Trading
Decentralized exchanges provide another important example of cross-chain liquidity in practice. Traditional decentralized exchanges generally operate within a particular blockchain environment, using liquidity pools or order-book mechanisms to facilitate trades.
Cross-chain trading systems attempt to connect these separate markets so users can exchange assets without manually managing every intermediate step.
Depending on the design, a cross-chain trading service may use a combination of routing algorithms, liquidity providers, bridges, smart contracts, and messaging protocols. Some systems source liquidity from destination-chain pools, while others coordinate transactions across multiple networks.
Imagine that a user wants to exchange a token on one network for a different token on another. A cross-chain trading interface may identify a route that transfers value, performs one or more swaps, and delivers the intended destination asset.
However, the displayed quote is only one part of the decision. Users should also understand whether the route depends on a bridge, whether the swap can fail, how refunds or recovery work, and whether the final amount is guaranteed or subject to changing market conditions.
The most important evaluation factors include:
- Quoted output: The estimated amount of the destination asset.
- Price impact: The effect of the trade on the relevant liquidity pools.
- Slippage tolerance: The permitted difference between the expected and executed result.
- Protocol fees: Charges imposed by the trading or routing service.
- Network fees: Costs associated with executing transactions on the relevant chains.
- Execution conditions: Requirements that must be met for the route to complete successfully.
- Security model: The contracts, validators, relayers, or liquidity providers involved in execution.
A route that appears inexpensive may expose users to greater risk or produce a worse final result under changing market conditions. Comparing the complete transaction is therefore more useful than comparing a single fee.
12.5 Liquidity-Based Bridges and Faster Transfers
Some cross-chain services use liquidity pools or professional liquidity providers to deliver assets on a destination network without requiring the user to wait for every step of a conventional bridge process.
In a simplified liquidity-based model, a provider sends the destination asset to the user and later settles the corresponding value through the system’s underlying mechanism.
This approach can improve the user experience when sufficient destination liquidity is available. Instead of waiting for a transfer to complete through a slower settlement path, users may receive their destination assets more quickly.
However, fast delivery does not remove the need for settlement, risk management, or sufficient liquidity. The provider must manage capital across supported networks and maintain enough inventory to satisfy user demand.
If demand becomes unbalanced, a provider may run low on an asset on one network. This can lead to higher fees, reduced transfer limits, delayed transactions, or temporary unavailability.
Liquidity-based services may also use different mechanisms to manage failed transactions, provider solvency, and settlement disputes. Users should understand those arrangements before relying on a service for significant transfers.
This model illustrates the relationship between capital efficiency and service quality. Maintaining liquidity on multiple chains can make transfers faster, but it also requires providers to manage inventory, operational costs, and exposure to cross-chain infrastructure.
12.6 Cross-Chain Lending and Collateral Management
Cross-chain liquidity can also expand the way users access decentralized lending and borrowing applications.
In a conventional lending market, users generally deposit supported assets into a protocol operating on a particular network. The protocol evaluates collateral and borrowing positions according to its own rules.
Cross-chain lending designs may allow users to interact with lending markets on another network or coordinate collateral and borrowing activities across multiple blockchain environments. The exact model depends on the protocol and its technical architecture.
For example, a user may hold a digital asset on one blockchain but want to access a lending market on another blockchain. The user may need to transfer collateral, use a supported cross-chain lending system, or obtain an asset accepted by the destination market.
These options involve different risks. Transferring collateral may expose the user to bridge and transaction risks. Using a cross-chain lending system may introduce additional smart contracts, messaging dependencies, or liquidation mechanisms.
Collateral management becomes more complicated when prices move rapidly or when the networks involved experience congestion. A delay in delivering collateral or processing a repayment could affect the user’s ability to maintain a healthy position.
Before using cross-chain lending, participants should examine:
- Which assets are accepted as collateral.
- How collateral values are calculated.
- How liquidation thresholds are determined.
- Whether cross-chain messages can be delayed or fail.
- What happens when a bridge or external protocol becomes unavailable.
- Whether the system depends on wrapped assets or third-party custodians.
- How users can repay loans or withdraw collateral during market stress.
Cross-chain lending can improve access to capital, but interconnected systems also create additional dependencies. A risk originating in one protocol may affect users who interact with another protocol through a shared asset or transfer mechanism.
12.7 Liquidity Aggregation Across Networks
Liquidity aggregation systems attempt to find suitable trading or transfer routes across supported venues and blockchain ecosystems.
Instead of requiring users to compare every exchange, bridge, and liquidity pool manually, an aggregator may evaluate multiple options and present a proposed route.
For example, a user transferring value between two networks may have several possible choices. One route may offer a lower fee but take longer. Another may complete more quickly but depend on a different bridge or liquidity provider. A third may require an intermediate asset or additional swap.
An aggregator can help compare these alternatives, although its results depend on the routes, liquidity sources, pricing information, and risk factors it supports.
Users should not assume that every aggregator examines every available route or fully measures every security risk. A route-ranking system may prioritize price, speed, or execution probability without providing a complete assessment of the underlying trust assumptions.
A careful comparison should include the expected destination amount, total fees, route complexity, transfer limits, expected execution time, and recovery options if a step fails.
Liquidity aggregation demonstrates how cross-chain infrastructure can simplify a fragmented market. However, the quality of the result still depends on the accuracy of the information and the reliability of the services involved.
12.8 What These Examples Reveal About Cross-Chain Liquidity
The examples above show that cross-chain liquidity is not a single product or technology. It is a collection of systems that help users access capital and applications across separate blockchain environments.
Ethereum and Layer-2 networks illustrate how liquidity can remain fragmented even when networks are closely connected. Independent Layer-1 blockchains demonstrate the additional challenges of connecting different architectures. Stablecoins show why consistent value transfer matters, while decentralized exchanges and aggregators reveal how routing and trading can be coordinated across networks.
Cross-chain lending highlights the importance of managing collateral and liquidation risk. Liquidity-based bridges demonstrate how providers can improve transfer speed by maintaining capital on multiple chains, while also introducing inventory and settlement requirements.
These examples also reveal a broader principle: greater connectivity does not automatically mean greater security, lower costs, or deeper liquidity. Every cross-chain route has its own technical design, economic conditions, and trust assumptions.
For users, the practical objective is to select a route that fits the transaction’s purpose while understanding the risks and costs involved. For developers and liquidity providers, the challenge is to make cross-chain activity more efficient without creating unnecessary dependencies or weakening security.
As blockchain ecosystems continue to develop, cross-chain liquidity will remain an important part of making decentralized finance more accessible. Its long-term success will depend on reliable infrastructure, transparent execution, sustainable liquidity, and security models that users can evaluate with confidence.
Institutional Capital and Cross-Chain DeFi
Institutional participation is becoming an important consideration in the development of digital asset markets. Asset managers, financial technology companies, trading firms, custodians, and other professional organizations are exploring how blockchain infrastructure can support trading, settlement, payments, tokenization, and decentralized financial services.
As these activities expand across different blockchain ecosystems, cross-chain liquidity becomes increasingly relevant. Institutions may need to move digital assets between networks, access liquidity in different markets, manage collateral, or interact with tokenized financial products operating on separate blockchain infrastructures.
However, institutional adoption requires more than the ability to transfer tokens between networks. Organizations must also evaluate operational controls, security, regulatory obligations, transaction transparency, counterparty exposure, and the reliability of the systems supporting each transfer.
Cross-chain DeFi could help institutions access a broader range of blockchain-based financial services, but its development will depend on whether the infrastructure can meet the demanding requirements of professional capital management.
13.1 Why Institutions Need Cross-Chain Liquidity
Institutional investors generally operate under defined investment strategies, risk limits, reporting requirements, and operational procedures. When digital assets and decentralized financial services are distributed across multiple blockchains, institutions may need reliable ways to access different markets without creating unnecessary operational complexity.
For example, a trading firm may hold stablecoins on one blockchain but need liquidity on another network to execute a trade. A digital asset manager may want to rebalance positions across several supported ecosystems. A financial technology company may need to move tokenized assets between compatible settlement environments.
Without effective cross-chain infrastructure, these activities can require separate accounts, additional transfer steps, fragmented liquidity management, and more complicated monitoring.
Cross-chain liquidity can help institutions address several objectives:
- Market access: Reach trading venues and decentralized applications across supported networks.
- Capital efficiency: Reduce the need to maintain unnecessarily large idle balances on every blockchain.
- Portfolio management: Move supported assets between ecosystems as market conditions change.
- Collateral mobility: Transfer or coordinate eligible collateral where the relevant infrastructure supports it.
- Settlement flexibility: Access different blockchain environments for specific financial activities.
- Operational consistency: Use integrated systems to monitor transfers, transaction costs, and asset balances.
These benefits depend on the available infrastructure and the institution’s requirements. A transfer mechanism that works well for a small retail transaction may not provide the controls, liquidity capacity, or reporting needed for a large institutional transaction.
Institutions must therefore evaluate cross-chain liquidity as part of their broader financial infrastructure rather than treating it as a simple token-transfer feature.
13.2 Institutional Liquidity Management Across Blockchains
Liquidity management involves ensuring that sufficient funds or assets are available where they are needed. In traditional financial markets, institutions manage cash, securities, collateral, and settlement balances across accounts, trading venues, and jurisdictions.
Blockchain-based markets introduce a similar challenge, but assets may be distributed across networks with different technical designs and transaction requirements.
An institution participating in several blockchain ecosystems may need to maintain enough capital to meet expected trading activity, collateral obligations, and withdrawal requests. Keeping excessive balances on every network can reduce capital efficiency, while maintaining too little liquidity can delay transactions or prevent an institution from responding effectively to market opportunities.
Cross-chain liquidity services may help organizations rebalance assets between supported networks. Automated treasury systems could monitor balances, estimate transaction costs, and identify when a transfer may be useful.
For example, suppose a digital asset trading firm holds stablecoins on two networks. Trading activity increases on one network, creating a need for additional capital. A treasury system could identify the imbalance and evaluate possible transfer routes.
Before executing a transfer, the system would need to consider network fees, bridge or service fees, available liquidity, transaction limits, expected completion time, and the security assumptions of the chosen route.
It may also need to consider whether moving the funds is economically justified. If transfer costs exceed the expected benefit of deploying the capital, keeping the existing allocation may be preferable.
Effective cross-chain treasury management therefore requires a balance between capital availability, transaction efficiency, and risk control.
13.3 Cross-Chain DeFi and Institutional Trading
Decentralized finance offers trading, lending, borrowing, derivatives, and other financial services through blockchain-based protocols. Institutions interested in these services may seek access to multiple ecosystems because liquidity and market opportunities are not evenly distributed.
One decentralized exchange may offer better liquidity for a particular trading pair, while another network may support an application with different transaction costs or market characteristics.
Cross-chain trading infrastructure can help institutions reach these opportunities by coordinating transfers and transactions across supported networks.
However, institutional execution involves several additional considerations.
First, the institution must determine whether the destination market can accommodate the intended trade. A route that works for a small transaction may experience substantial price impact when used for a larger order.
Second, the institution needs to understand the execution process. Some routes may involve several transactions, external liquidity providers, smart contracts, or cross-chain messaging systems. Each additional dependency can create operational or technical risk.
Third, institutions generally require clear records of transaction execution, asset movements, fees, and resulting balances. A cross-chain trading system should provide sufficient information to support internal reconciliation and applicable reporting obligations.
Finally, institutions must determine whether the relevant trading activities and counterparties comply with their legal, regulatory, and internal policy requirements.
Cross-chain DeFi can expand market access, but institutions must assess whether the available infrastructure is suitable for the size, frequency, and complexity of their transactions.
13.4 Tokenized Assets and Cross-Chain Settlement
Tokenization involves representing rights to an asset or financial instrument through a digital token. Depending on the legal structure, the token may represent ownership, a claim, a contractual entitlement, or another defined interest.
Potential applications include tokenized funds, debt instruments, money-market products, and other financial assets. Some projects explore issuing or managing these tokens across multiple blockchain environments.
Cross-chain liquidity becomes important when tokenized assets and the funds used to purchase, redeem, or settle them operate on different networks.
For example, a tokenized financial product may be available through one blockchain-based platform, while a potential investor holds the required payment asset on another network. Cross-chain infrastructure may help coordinate the movement of funds or connect compatible settlement systems.
Yet tokenization does not automatically make an asset transferable everywhere. The token’s legal terms, issuer restrictions, eligibility requirements, transfer controls, and technical design determine how it can be used.
A tokenized asset may also rely on a permissioned network or require approved participants. In such cases, open cross-chain connectivity may be limited by compliance requirements or access controls.
Institutional adoption will depend on several factors:
- Clear legal rights associated with the token.
- Reliable custody and asset-servicing arrangements.
- Compatible technical standards and transfer mechanisms.
- Secure settlement and reconciliation processes.
- Appropriate identity verification and compliance controls.
- Sufficient liquidity for issuance, trading, and redemption.
- Clearly defined procedures for resolving failed transactions.
Cross-chain settlement could help connect tokenized financial markets, but the underlying legal and operational arrangements must remain clear. Moving a token between networks does not necessarily transfer every legal right or guarantee that the asset can be redeemed under all circumstances.
13.5 Institutional Custody and Cross-Chain Security
Custody is a major consideration for institutions holding digital assets. Organizations need to protect private keys, authorize transactions appropriately, monitor balances, and maintain procedures for responding to security incidents.
Cross-chain activity adds complexity because the institution may interact with multiple networks, token standards, smart contracts, and transfer providers.
A secure custody arrangement must account for the assets being held and the transactions used to move them. The custody provider may need to support the relevant blockchain networks, verify destination addresses, apply approval policies, and maintain accurate transaction records.
Cross-chain operations can also involve assets held temporarily by a bridge, represented through wrapped tokens, or managed by a liquidity provider. Institutions need to understand the implications of these arrangements.
A token that appears in a wallet does not necessarily have the same risk profile as the native asset it represents. Its value and usability may depend on a separate contract, reserve arrangement, redemption process, or bridge mechanism.
Institutional security reviews should examine:
Private-key management: How are signing keys generated, stored, protected, and recovered?
Transaction authorization: Are transfers subject to approval thresholds, role separation, and transaction limits?
Smart contract exposure: Which contracts are involved, and what happens if one is compromised?
Bridge dependencies: Does the transfer rely on validators, external operators, liquidity providers, or cryptographic verification?
Asset verification: Can the institution distinguish native assets from wrapped or bridged representations?
Monitoring and incident response: Are unusual transfers detected, and are procedures available to respond to an exploit or service disruption?
Recovery procedures: What options exist if a transfer becomes delayed, fails, or reaches an unintended destination?
Institutional custody must be designed around the entire transaction lifecycle, not merely the security of the wallet holding the final asset.
13.6 Compliance, Transparency, and Governance
Institutions operate within legal and regulatory frameworks that may impose obligations relating to customer identification, sanctions screening, anti-money-laundering controls, financial reporting, recordkeeping, and risk management.
The exact requirements vary according to jurisdiction, activity, organizational role, and the nature of the asset or service.
Cross-chain transactions can complicate compliance because assets may pass through multiple networks, protocols, liquidity providers, or wallet addresses. Information about the origin and destination of funds may be distributed across several systems.
Institutions may therefore need monitoring tools that can trace relevant transactions across supported networks and maintain records of the routes used.
However, blockchain transparency does not automatically establish the identity of a wallet owner or demonstrate that a transaction complies with applicable requirements. On-chain data often needs to be interpreted alongside additional information, organizational policies, and relevant legal obligations.
Governance also matters. Some cross-chain protocols allow designated administrators to upgrade contracts, change parameters, pause functionality, or manage emergency situations. Other systems distribute authority across validators or governance participants.
Institutions must understand these powers before integrating a protocol into critical operations. An upgrade mechanism may help address vulnerabilities, but it can also introduce administrative control and additional trust assumptions.
A responsible institutional framework should document the relevant dependencies, assign accountability, and define how protocol changes or security incidents will be handled.
13.7 Liquidity Providers and Professional Market Makers
Professional liquidity providers and market makers can play an important role in connecting blockchain ecosystems. They may supply assets to liquidity pools, quote prices, execute swaps, or provide inventory for cross-chain transfer services.
Maintaining liquidity across several networks requires capital allocation, monitoring, and risk management. Providers must determine where assets are needed, how quickly inventory can be replenished, and whether the expected returns justify the costs and risks.
For example, a market maker may provide liquidity for a stablecoin pair on two networks. If trading demand increases sharply on one network, the provider may need to rebalance inventory or acquire additional assets to maintain competitive prices.
Cross-chain transfer services can support this process, but rebalancing is not always instantaneous or inexpensive. Network congestion, transfer limits, liquidity shortages, and security incidents can delay the movement of funds.
Market makers also face risks associated with changing prices, adverse selection, smart contract vulnerabilities, and temporary imbalances between markets.
Professional liquidity management may improve market depth and reduce trading friction. Nevertheless, institutional participation does not guarantee that liquidity will remain available during periods of extreme volatility or market stress.
The resilience of a cross-chain market depends on the diversity of liquidity providers, the reliability of transfer infrastructure, and the incentives that encourage providers to continue operating under changing conditions.
13.8 Risk Management for Institutional Cross-Chain Operations
Institutions generally need a structured process for identifying, measuring, and controlling risk. Cross-chain transactions should be evaluated according to their economic purpose, transaction size, operational requirements, and underlying technical dependencies.
A useful framework separates several categories of risk.
Technology risk: Smart contract bugs, consensus failures, software defects, and vulnerabilities in cross-chain messaging systems.
Counterparty risk: Exposure to custodians, bridge operators, liquidity providers, service providers, or other parties that may fail to meet their obligations.
Liquidity risk: Insufficient assets available to execute a trade, complete a transfer, or satisfy withdrawal demands.
Market risk: Price volatility, slippage, depegging, and changes in the value of collateral or tokenized assets.
Operational risk: Incorrect addresses, authorization mistakes, failed procedures, monitoring gaps, and delays in responding to incidents.
Compliance risk: Failure to satisfy applicable legal, regulatory, recordkeeping, or internal policy requirements.
Concentration risk: Excessive dependence on a single bridge, validator group, liquidity provider, custody service, or messaging protocol.
These categories can overlap. A technical exploit may reduce liquidity, trigger price movements, and create operational difficulties at the same time.
Institutions can reduce unnecessary exposure by setting transaction limits, reviewing protocol security, diversifying infrastructure where appropriate, maintaining emergency procedures, and testing recovery processes.
They should also recognize that diversification does not eliminate all risk. Several services may depend on the same underlying blockchain, security provider, stablecoin, or software component. Effective risk management requires identifying these shared dependencies.
13.9 Can Cross-Chain DeFi Meet Institutional Requirements?
The suitability of cross-chain DeFi for institutions depends on the specific use case and the maturity of the infrastructure.
Some organizations may be comfortable using supported blockchain networks for limited transfers or carefully controlled trading activities. Others may require extensive technical reviews, contractual protections, insurance arrangements, permissioned access, or additional operational safeguards before using a cross-chain system.
Institutions typically evaluate more than transaction speed. They also consider the predictability of execution, liquidity depth, asset custody, legal arrangements, governance, incident response, and the availability of reliable transaction records.
A protocol may offer attractive features but remain unsuitable for a particular institution if it lacks sufficient liquidity, has unclear administrative controls, or depends on infrastructure that does not meet the organization’s security requirements.
Conversely, a carefully evaluated cross-chain system may help an institution reach additional markets, manage capital more efficiently, or support a specific tokenized-asset workflow.
The key is to match the technology to the use case rather than assuming that every cross-chain product is appropriate for every professional participant.
13.10 The Future of Institutional Cross-Chain Liquidity
Institutional cross-chain infrastructure is likely to evolve alongside improvements in interoperability, digital asset custody, tokenization, and blockchain-based settlement.
Potential developments include more standardized transfer interfaces, stronger verification mechanisms, improved liquidity routing, better transaction monitoring, and integrated treasury-management tools.
Institutions may also explore infrastructure designed for particular financial activities, including tokenized funds, digital securities, payments, and collateral management.
However, progress will depend on the ability of different systems to communicate reliably while preserving appropriate security and compliance controls. Greater automation may improve efficiency, but it can also introduce new dependencies if institutions do not maintain adequate oversight.
The most successful solutions will need to demonstrate that they can operate reliably under normal conditions and respond appropriately when networks become congested, liquidity declines, or technical problems occur.
Ultimately, cross-chain liquidity can help institutional capital move more efficiently across blockchain ecosystems. Its long-term role will depend on transparent risk management, dependable infrastructure, sustainable liquidity, and clear operational accountability.
For institutional participants, the goal is not simply to connect more blockchains. It is to connect them in ways that make financial activity more efficient without compromising security, governance, or responsible asset management.
The Future of Cross-Chain Liquidity
Cross-chain liquidity is an important part of the broader effort to make blockchain ecosystems more connected, efficient, and accessible. As decentralized finance expands across Layer-1 blockchains, Layer-2 networks, and specialized blockchain environments, the ability to move assets and interact with applications across these systems will continue to influence how digital financial markets develop.
Today, liquidity is often fragmented across networks, trading platforms, and token representations. Users may need to navigate different bridges, decentralized exchanges, liquidity pools, and transfer services to complete a single financial activity. These processes can create additional costs, delays, and security considerations.
Future cross-chain infrastructure aims to reduce this complexity. Improvements in interoperability, liquidity aggregation, cryptographic verification, transaction automation, and blockchain standards could make cross-chain transactions easier to execute and manage.
However, the future of cross-chain liquidity will not be determined by connectivity alone. The industry must also address security, liquidity sustainability, operational reliability, and the risks created when multiple systems depend on one another.
14.1 More Advanced Blockchain Interoperability
Interoperability is likely to remain one of the most important areas of cross-chain development. As blockchain networks become more specialized, applications may increasingly rely on several networks rather than operating entirely within a single ecosystem.
Future interoperability systems could improve how blockchains exchange messages, verify events, and coordinate transactions. Better standards may also make it easier for applications to communicate with supported networks without requiring developers to create a separate integration for every possible connection.
For example, a decentralized financial application may eventually be able to request a cross-chain operation through a standardized interface. The underlying infrastructure could identify the relevant networks, evaluate supported execution routes, and coordinate the required steps.
Such systems could simplify the user experience, but standardized interfaces would not eliminate differences between blockchains. Each network would still have its own security model, transaction rules, and finality characteristics.
Developers would need to understand what happens when a message arrives late, a transaction fails, or one of the connected networks becomes unavailable.
The most useful interoperability solutions will combine easier integration with clear security assumptions and dependable failure-handling mechanisms.
14.2 Unified Liquidity Access Across Multiple Networks
One of the long-term goals of cross-chain infrastructure is to make fragmented liquidity easier to access.
At present, an asset may have substantial trading activity on one network but limited liquidity on another. Users may need to transfer funds, perform intermediate swaps, or navigate several applications to reach the desired market.
Future liquidity systems could improve the process by combining information from multiple exchanges, pools, and transfer providers. Routing systems may become better at comparing total costs, estimating execution quality, and selecting appropriate routes for individual transactions.
A user might specify the asset they want to send, the asset they want to receive, and the destination network. The interface could then present supported options based on expected output, fees, estimated completion time, and other relevant conditions.
Nevertheless, unified access does not mean that all liquidity becomes one shared pool. Assets remain subject to the liquidity available on their respective networks, and routes depend on functioning infrastructure.
A system may identify an attractive opportunity but still be unable to execute it if liquidity disappears, network conditions change, or a required service becomes unavailable.
The future challenge is therefore to improve liquidity discovery and execution without overstating how much capital is genuinely accessible across connected markets.
14.3 Intent-Based Cross-Chain Transactions
Intent-based systems represent another potential development in cross-chain liquidity.
Instead of requiring users to specify every technical step, an intent-based interface allows them to describe the result they want to achieve. Specialized solvers or routing systems then attempt to fulfill that request using supported liquidity sources and execution mechanisms.
For example, a user may want to exchange an asset on one blockchain for a different asset on another network while receiving at least a specified minimum amount. The system could evaluate possible routes and identify a solution that satisfies the user’s stated conditions.
This approach could reduce the need for users to understand every bridge, swap, and intermediate transaction involved in a complex route.
Intent-based systems may also encourage competition between solvers. Depending on the design, solvers may compete on execution quality, price, speed, or other criteria.
However, intent-based execution introduces its own considerations. Users need to understand how solvers are selected, what happens when an intent cannot be fulfilled, and whether the execution process exposes them to additional counterparty or protocol risk.
A clearly stated intent does not guarantee successful execution under all market conditions. Liquidity may change, transaction costs may rise, and some routes may become unavailable before completion.
For intent-based cross-chain liquidity to become more dependable, systems will need transparent execution rules, strong settlement guarantees where feasible, and reliable methods for handling unsuccessful transactions.
14.4 Improvements in Cryptographic Verification
Security remains a major challenge for cross-chain infrastructure. A transfer system must establish that an event occurred on one network before allowing another network or service to act on that information.
Different systems use different verification approaches, including validator attestations, light clients, cryptographic proofs, and other mechanisms designed to establish the validity of cross-chain messages.
Future improvements in cryptographic verification could make it easier to validate certain blockchain events with stronger guarantees or lower verification costs.
For example, proof-based systems may allow a destination application to verify information about a source-chain event without relying entirely on a conventional intermediary’s statement. The practical security benefits depend on the proof system, the implementation, and the assumptions required to generate and verify the proof.
More advanced verification could reduce some forms of trust dependence, but it would not remove every possible vulnerability. Smart contract bugs, incorrect implementations, compromised administrative keys, and weaknesses in connected applications could still create risks.
The industry will therefore need to combine technical advances with independent security reviews, transparent upgrade processes, and clear explanations of what each verification mechanism actually guarantees.
14.5 Smarter Liquidity Routing and Automated Capital Allocation
Liquidity routing systems may become more sophisticated as they gain access to better pricing information and more advanced execution tools.
A future routing system could evaluate liquidity across supported exchanges and networks, estimate transaction costs, consider execution delays, and assess whether a proposed route meets specified risk and price conditions.
For professional liquidity providers, automated capital-allocation tools could also help monitor asset balances across networks. These tools might identify where liquidity is needed, estimate the cost of rebalancing, and recommend whether capital should be moved.
Consider a market maker that operates across several blockchain ecosystems. If trading demand increases on one network, an automated system could compare the cost of transferring inventory with the potential benefit of supplying additional liquidity.
The system would need to account for network fees, bridge risk, available inventory, price volatility, and expected trading demand. Moving capital simply because a network offers a higher trading volume would not necessarily be profitable.
Automation could make liquidity management more efficient, but it could also amplify errors if its assumptions are incorrect or its controls are inadequate.
Future systems will need safeguards such as transaction limits, monitoring, human approval for sensitive operations, and procedures for pausing activity when market or network conditions become abnormal.
14.6 Account Abstraction and a Simpler User Experience
Cross-chain transactions can be difficult for users who must manage multiple wallets, network-specific gas tokens, transaction approvals, and separate interfaces.
Account abstraction and programmable wallet designs may help simplify some of these interactions. Depending on the implementation, users could benefit from more flexible authorization rules, transaction batching, sponsored transaction fees, or automated wallet operations.
For example, a supported wallet could help a user complete a transaction without manually obtaining a small amount of the destination network’s native token first. Another wallet design might allow several related actions to be grouped into a simpler interface.
These features could make cross-chain liquidity more accessible to people who are unfamiliar with blockchain infrastructure.
However, account abstraction does not automatically provide cross-chain execution. The wallet still needs compatible applications, transfer services, or interoperability mechanisms to perform actions across separate networks.
Users must also understand the security implications of programmable permissions, recovery systems, transaction sponsorship, and third-party services.
A simpler interface should make complex operations easier to understand, not hide important information about fees, token representations, or security risks.
14.7 Cross-Chain Stablecoins and Digital Payments
Stablecoins may continue to play an important role in cross-chain liquidity because they are used for trading, transferring value, and accessing decentralized financial services.
As stablecoin infrastructure develops, users and businesses may seek more reliable ways to move value between supported blockchain networks. This could benefit digital payments, blockchain-based settlement, and applications that need access to dollar-denominated assets across different ecosystems.
Future systems may improve the consistency of stablecoin transfers, reduce unnecessary conversion steps, and make it easier for applications to identify supported assets.
However, stablecoins issued on different networks can have different technical and operational characteristics. Some may be native assets issued under the issuer’s control, while others may be representations created through third-party bridging arrangements.
The distinction affects redemption, security, and liquidity. A token’s availability on a particular blockchain does not necessarily mean it has the same redemption conditions or risk profile as another token with a similar name.
Businesses using cross-chain stablecoins will need to assess issuer arrangements, transfer mechanisms, regulatory requirements, transaction costs, and access to reliable exit routes.
The future of cross-chain payments will depend not only on speed and convenience but also on the ability to move value reliably and understand the obligations associated with each asset.
14.8 Tokenization and Connected Financial Markets
Tokenization could expand the role of cross-chain liquidity by creating digital representations of financial assets that operate on blockchain infrastructure.
Potential use cases include tokenized funds, debt instruments, payment assets, and other financial products. As different organizations adopt blockchain systems, there may be a growing need to connect compatible assets and settlement processes across networks.
Cross-chain infrastructure could help coordinate transfers between supported environments, enabling certain assets or payment mechanisms to interact with applications operating elsewhere.
For example, a tokenized financial product may exist on one network while an eligible investor uses a compatible settlement asset on another. An interoperability system could help coordinate the required actions, subject to the product’s legal and technical restrictions.
However, tokenization does not automatically create an open or liquid market. Some assets may be subject to eligibility rules, transfer restrictions, issuer approval, or jurisdiction-specific requirements.
The legal rights associated with a token must also remain clear when it moves between systems. A technical transfer cannot, by itself, establish ownership rights that are not supported by the relevant legal arrangements.
Cross-chain tokenization will therefore require collaboration among blockchain developers, financial institutions, custodians, asset issuers, and regulators where appropriate.
14.9 Better Risk Monitoring and Real-Time Security Controls
As cross-chain activity expands, monitoring systems will become increasingly important.
A cross-chain transaction may involve multiple smart contracts, validators, liquidity providers, and blockchain networks. Identifying a problem quickly can be difficult when information is distributed across several systems.
Future monitoring tools may combine on-chain activity, liquidity information, transaction histories, and security alerts to help users and service providers identify abnormal conditions.
For example, a monitoring system might flag an unusual increase in bridge outflows, a sharp decline in liquidity, repeated transaction failures, or an unexpected change in a protocol’s administrative settings.
Automated controls could respond by limiting transaction sizes, requiring additional authorization, or temporarily suspending certain operations when predefined risk conditions are met.
However, monitoring systems can produce false alarms or fail to detect unfamiliar attack patterns. Automated responses can also disrupt legitimate transactions if thresholds are poorly configured.
Security monitoring should therefore be combined with tested incident-response procedures, independent oversight, and transparent communication about the limits of automated detection.
The objective is not to promise that cross-chain systems can never fail. It is to improve the ability to detect problems, limit their impact, and respond effectively when incidents occur.
14.10 The Role of Decentralization and Governance
Future cross-chain infrastructure will continue to face a balance between decentralization, efficiency, and operational control.
Some systems rely on a limited set of validators or service providers to coordinate transactions. Others use more distributed verification mechanisms or cryptographic techniques designed to reduce reliance on intermediaries.
More decentralized designs may reduce certain forms of concentrated control, but decentralization alone does not guarantee security. A system can distribute authority widely while still containing vulnerable contracts, weak economic incentives, or flawed verification logic.
Governance also affects how protocols respond to emergencies, upgrade software, and change transaction rules.
For example, an emergency pause mechanism may help prevent further losses during a security incident. At the same time, users need to know who can activate that mechanism, what authority administrators possess, and how the system returns to normal operation.
Future protocols may develop clearer governance disclosures, stronger controls over privileged operations, and more transparent processes for reviewing significant changes.
Users and institutions will benefit when they can understand not only how a cross-chain transaction is executed but also who can change the rules governing that transaction.
14.11 Will Cross-Chain Liquidity Become Invisible to Users?
One possible direction is that cross-chain complexity becomes less visible to ordinary users.
Today, users may need to select a source network, destination network, bridge, token representation, and transaction route. They may also need to manage network-specific fees and understand the differences between supported assets.
Future applications could handle more of these steps automatically. Users might select the asset they want to send and the asset they want to receive, while the application identifies a supported route and presents the expected result.
This could make blockchain applications more approachable and reduce mistakes caused by confusing network settings.
However, hiding technical complexity creates a responsibility to communicate important information clearly. Users should still be able to understand the expected amount, transaction costs, execution conditions, and material risks.
Applications should also provide meaningful information about failures and recovery options rather than leaving users uncertain about the status of their assets.
The ideal experience would simplify routine decisions while preserving transparency and user control over important financial actions.
14.12 Challenges That Could Slow Adoption
Despite its potential, cross-chain liquidity faces several challenges that could slow widespread adoption.
Security incidents: Major exploits or repeated failures could reduce user confidence and discourage institutions from using certain services.
Fragmented standards: Differences between blockchain architectures and token implementations can make interoperability more complicated.
Liquidity shortages: Some networks may lack sufficient trading depth or transfer inventory to support large transactions efficiently.
Regulatory uncertainty: Requirements may differ across jurisdictions, assets, service providers, and financial activities.
Operational complexity: Managing multiple networks, contracts, and providers can increase monitoring and reconciliation costs.
Unclear accountability: Users may struggle to determine which party is responsible when a transaction fails or an intermediary becomes unavailable.
Economic sustainability: Cross-chain providers need business models and incentives that support reliable infrastructure without relying on unsustainable rewards.
User education: People must understand important differences between native assets, wrapped tokens, bridges, and cross-chain swaps.
Addressing these challenges will require more than new technology. It will also require better documentation, reliable service operations, realistic risk disclosures, and continued collaboration across blockchain ecosystems.
14.13 What a More Connected Blockchain Economy Could Look Like
A more connected blockchain economy would allow users and applications to access supported digital assets and financial services across networks with fewer unnecessary barriers.
Liquidity providers could allocate capital more efficiently. Traders could compare execution routes more easily. Businesses could use suitable blockchain infrastructure for payments and settlement. Developers could build applications that interact with multiple networks without implementing every connection independently.
Yet this future does not require every blockchain to become identical or every asset to be available everywhere.
Different networks may continue to specialize in particular activities, including smart contract execution, payments, privacy, data availability, or financial settlement. Cross-chain infrastructure would connect these environments while respecting their technical and operational differences.
The strongest systems will likely be those that make connectivity useful without treating security as an afterthought. They will need to offer reliable execution, understandable costs, sufficient liquidity, and transparent mechanisms for managing failures.
Ultimately, cross-chain liquidity could help digital finance become more flexible and accessible. Its success will depend on whether the industry can combine interoperability and capital efficiency with strong security, clear governance, and realistic expectations about what connected systems can achieve.
Conclusion and Key Takeaways
Cross-chain liquidity is becoming an increasingly important component of the blockchain economy. As digital assets, decentralized applications, and financial services expand across multiple blockchain ecosystems, the ability to move capital between networks can help users access new markets, improve capital utilization, and participate in a wider range of financial activities.
However, blockchain networks do not automatically share their liquidity. Each ecosystem has its own assets, applications, transaction costs, security arrangements, and market conditions. This fragmentation can create challenges for traders, liquidity providers, developers, and institutions seeking to move value efficiently between networks.
Cross-chain liquidity solutions attempt to address these challenges through several complementary technologies, including blockchain bridges, cross-chain liquidity pools, decentralized exchanges, atomic swaps, interoperability protocols, wrapped assets, and liquidity aggregation systems.
Each approach offers different benefits and limitations. Bridges can enable asset transfers between networks, liquidity pools support trading, interoperability protocols coordinate messages, and aggregators help identify suitable transaction routes. Wrapped assets can represent value across ecosystems, while atomic swaps offer specialized mechanisms for exchanging assets without relying on every conventional bridging arrangement.
Understanding these differences is essential because cross-chain transactions involve more than moving tokens from one wallet to another. Users must consider how assets are represented, how transactions are verified, which parties or contracts are involved, and what happens if an operation fails.
Why Cross-Chain Liquidity Matters
One of the main benefits of cross-chain liquidity is improved access to blockchain-based financial services.
Users may be able to access decentralized exchanges, lending protocols, payment applications, and other services that operate on different networks. Liquidity providers can support trading activity across multiple ecosystems, while developers can build applications that interact with supported networks.
Cross-chain infrastructure may also improve capital efficiency by making it easier to allocate assets where they are needed. Instead of managing every blockchain as an entirely isolated environment, participants can use transfer and routing mechanisms to connect supported markets.
Stablecoins and tokenized assets may further increase the importance of this infrastructure as businesses and financial institutions explore blockchain-based payments, trading, and settlement.
Nevertheless, these benefits depend on actual liquidity, reliable infrastructure, compatible assets, and manageable transaction costs. Greater connectivity does not automatically guarantee better prices, faster execution, or lower risk.
The Importance of Security and Risk Management
Security remains one of the most important challenges facing cross-chain liquidity.
A transaction may depend on multiple smart contracts, blockchain networks, validators, liquidity providers, or messaging systems. A weakness in one component can affect the reliability of the entire route.
Bridge vulnerabilities, compromised administrative keys, insufficient liquidity, wrapped-token depegging, transaction delays, and smart contract failures can all create potential losses.
Users should therefore evaluate the complete transaction process rather than focusing only on the advertised transfer speed or fee.
Before moving significant assets, they should verify the destination network and token, review the transfer mechanism, understand the relevant trust assumptions, and consider the consequences of a failed transaction. Testing a new route with a small amount may also help users identify operational problems before committing larger sums.
Liquidity providers and institutions require additional safeguards, including transaction limits, security reviews, monitoring, contingency planning, and clear procedures for responding to incidents.
No cross-chain solution can eliminate every risk. Responsible participation depends on understanding the risks that remain and choosing infrastructure appropriate to the transaction’s purpose.
What the Future Holds for Cross-Chain Liquidity
The future of cross-chain liquidity will likely involve continued improvements in interoperability, cryptographic verification, liquidity routing, transaction automation, and user experience.
More advanced systems may simplify how users access assets across supported networks. Intent-based execution could reduce the number of technical steps users must manage, while improved routing systems may help compare available liquidity and transaction costs.
Institutional participants may also explore cross-chain infrastructure for treasury management, tokenized assets, digital payments, and decentralized financial services.
However, progress will depend on more than technical innovation. The industry must also improve transparency, establish sustainable economic incentives, strengthen operational controls, and make the security assumptions of cross-chain systems easier to understand.
Different blockchains may continue to serve different purposes rather than merging into one universal network. Cross-chain liquidity can help connect these ecosystems while allowing them to retain their distinct technical characteristics.
The long-term objective is not simply to connect as many blockchains as possible. It is to make those connections useful, reliable, and secure enough to support real financial activity.
Key Takeaways About Cross-Chain Liquidity
The following points summarize the most important lessons from this article:
- Cross-chain liquidity connects blockchain ecosystems. It helps users and applications access assets and financial services across supported networks.
- Liquidity fragmentation remains a major challenge. Assets and trading activity are distributed across different blockchains, exchanges, and liquidity pools.
- Several technologies support cross-chain activity. Bridges, liquidity pools, atomic swaps, interoperability protocols, wrapped assets, and aggregators perform different roles.
- Native and wrapped assets are not always equivalent in risk. Users should understand the origin, backing, redemption process, and security assumptions of the token they receive.
- Transaction costs involve more than network fees. Bridge charges, swap fees, price impact, slippage, and intermediate conversions can affect the final result.
- Liquidity availability affects execution quality. A route may become more expensive or unavailable when demand changes or destination liquidity declines.
- Security depends on the complete transaction route. Every relevant contract, verification mechanism, provider, and network can introduce additional dependencies.
- Cross-chain DeFi creates new opportunities and risks. Access to more markets can improve flexibility, but interconnected systems may also transmit disruptions between protocols.
- Institutions require stronger operational controls. Custody, compliance, monitoring, governance, and reliable transaction records are important considerations.
- Future improvements must balance efficiency and security. Better interoperability and automation will be most valuable when supported by transparent risk management and dependable infrastructure.
Final Thoughts
Cross-chain liquidity represents an important step toward a more connected digital financial environment. By helping capital move between blockchain ecosystems, it can reduce some barriers that prevent users and applications from accessing opportunities beyond a single network.
Its development may support broader participation in decentralized finance, improve the distribution of liquidity, and create new possibilities for blockchain-based trading, payments, lending, and tokenization.
Yet connectivity should never be confused with complete interoperability or guaranteed safety. Every cross-chain transaction depends on specific technical mechanisms, liquidity conditions, and trust assumptions. Understanding those factors is essential for making informed decisions.
For individual users, the priority should be choosing supported routes, verifying assets and destinations, understanding fees, and managing risk. For developers, it should be building systems that make cross-chain interactions more reliable and transparent. For institutions, it should be integrating cross-chain infrastructure into carefully managed operational and security frameworks.
As blockchain technology continues to evolve, cross-chain liquidity will remain an important area to watch. Its long-term success will depend on the industry’s ability to connect separate ecosystems without sacrificing the security, transparency, and reliability that digital financial markets require.
Ultimately, the goal of cross-chain liquidity is not merely to move capital between blockchains. It is to make digital assets more useful across connected ecosystems while preserving the trust and security needed for sustainable financial activity.